I. INTRODUCTION
The contribution of consumer goods companies is recognized across the globe. In Nigeria, although the consumer goods sector is growing, it is, however, experiencing stiff and fierce competition (Klynveld, Peat, Marwick & Goerdeler (KPMG), 2014; and Osundina, 2014) as cited by Kabuoh, Moibi, Ademilua & Babajide, (2020). To bolster this position, Yinka (2019), Agboifor (2018) and Zwingina and Opusunju (2017) documented that the high rate of collapse of the manufacturing industry especially in consumer goods firms in Nigeria and continuous decline in financial performance (profitability) is attributed to factors such as increased competitive landscape from globalization, the decline in consumers' purchasing power due to the inaccessibility of the dollar in the economy and delayed policy response, which have resulted in weak macroeconomic conditions, weak labour market dynamics (high unemployment and underemployment), reduced disposable income and poor corporate performance. The comprehensive study by Kabuoh, Moibi, Ademilua & Babajide, (2020) covering 2010-2016 indicates that of consumer goods companies reported dwindling performance showing the decline in the percentage increase in sales revenue and profitability. Consequently, this has posed a significant concern for the Nigerian government and policymakers.
To address the declining financial performance of the Nigerian consumer goods sector, the government, and public sector have evolved policies in an attempt to address identified loopholes and bolster the consumer goods sector. Interestingly, in 2017, the Nigerian government restricted or placed bans on certain imports destined for the country, especially in the food, drug, and cosmetics categories, which require some inspections, testing, and reviews, and clearance of imports is typically delayed to the detriment of the importer (International Trade Administration, 2020). Again, the International Trade Administration (2020) states that the Nigerian government has several import substitution policies which aim to increase local production over imports through subsidies, tariffs, quotas, and other trade barriers. Also, that the Federal Government of Nigeria has put in place directive that stipulates that preference be granted to domestic manufacturers in all government procurements. Moreover that at least expenditure for the procurement of manufacturing items such as; uniforms and footwear, food and beverages, furniture and fittings, stationery, motor vehicles, pharmaceuticals, construction materials, and information technology shall be on locally manufactured goods. In December, 2019, the Nigerian senate passed an amendment to the Public Procurement Act of 2007 which would, among other changes, compel Federal Government Ministries, Departments and, Agencies to show a preference for local consumer goods and services. Interestingly, despite these laudable programs, the consumer goods sector in Nigeria continues to experience declining financial performance (Kabuoh, Moibi, Ademilua & Babajide, 2020 and Yinka, 2019)
The poor state of the financial growth of consumer goods companies in Nigeria has, therefore, attracted academic research interest to explore the factors responsible for this present situation. However, strategies, organizational structure and systems, social networks, stretched resources, and environmental factors (Baum, Locke & Smith, 2001; Baum & Locke, 2004; Jin & Kirsch, 2015 and Donthu & Gustafsson, 2020); (Freeman, 1984; Peace, 1982; in Hills & Jones, 1992) have been suggested as factors that account for the poor state of financial growth of consumer goods firms. Interestingly, the literature by Carrol and Sabana (2010) and Fu & Jia (2013) explain why the concept of corporate social responsibility (CSR) is crucial in explaining a firm's financial performance in the field of accounting.
Though corporate social responsibility has been researched as a precursor to financial performance, few studies have considered the effects of the dimensions of corporate social responsibility on financial performance. Interestingly, these dimensions, as advanced by The Sino-German Corporate Social Responsibility Project (SGCSRP), (2012) and Inoue and Lee (2011), are employee relations, product quality, community relations, environment, diversity, and human rights. There in annual reports and accounts, corporations in Nigeria have aligned and reported their social responsibility mostly about responding to the environment, energy use, employees, the community and, products and customers. Interestingly, there is now a demand for companies to be socially responsible for prevent of COVID-19 (Ikram, Zhang, Sroufe, and Ferasso, 2020). The current study evaluated the effect of the contribution of corporate social responsibility on employees resulting in motivation, and corporate reputation on financial performance (FP). Interestingly, a search in the current literature on this critical factor from the Nigerian context reveals a lack of studies on the effect of this dimension on corporate reputation on financial performance.
The importance of the contribution of employees to an organization's financial performance, whether directly or indirectly, is enormous. Consequently, Akintoye (2012), while drawing inferences from some assertions on human capital, concluded that the human element is one of the most valuable inputs in an organization. To bolster this inference, Akintoye
(2012) observed, "A team of competent, devoted, and motivated persons can convert a sick concern into a successful one. Consequently on the other hand, incompetent and disinclined personnel may waste the existing physical and financial resources leading the concern to collapse" (p.566&567). The level to which employees are motivated via corporate social responsibility is presumed to have an effect on the financial performance.
Therefore, this research evaluated the degree to which corporate social responsibility on employees affects FP of listed consumer goods companies in Nigeria. Consequently, the hypothesis of the study is:
a) Corporate Social Responsibility on Employees has No Significant Effect on FP
Corporate entities will understand the effect of their corporate responsibility initiatives to the employees on financial performance. Consequently, this will necessitate optimal use of corporate responsibility to employees to enhance financial performance. Moreover, corporate employees will also understand the need to align their interests with the CSR posture of their organizations if they have not been doing so. Moreover, academics and students will use this study as referral material during their research. Moreover, this study might also give room for theorizing/hypothesizing other dimensions of CSR that affect FP. The remaining part of this study is divided into: literature review, methodology, results, and discussion of findings.
II. LITERATURE REVIEW
a) Conceptual Framework
i. Corporate Social Responsibility (CSR)
Many authors have defined the concept of CSR differently. Still, all these definitions convey that CSR is voluntary and encompasses business standards, principles, norms, ethics, policies, and practices integrated into the business culture to benefit stakeholders.
ii. Employees' Component of Corporate Social Responsibility
On the employees' component of CSR, CSR Hub in Aggarwal (2013) notes that it includes: disclosure of policies, programs, and performance in diversity, labour- relations and labour rights, compensation benefits, and employee training, health and safety, compliance with national laws and regulations, fair treatment of all employees, disclosure of workforce diversity data, strong labor codes, comprehensive benefits, training and development opportunities, and employee health and safety policies.
Additionally, Boztosun and Aksoylu (2015) remarked that CSR has four policies namely: business, environmental, market, and social policies. Moreover, the business policies of CSR cover the support given for long-term career prospects and development of employees, taking measures to prevent any discrimination in employment to promote the participation of employees in management and their contributions to critical decisions, bearing in mind the issues of improved health, security and welfare of employees.
A company's CSR efforts for employees entail providing safeworking conditions, training employees, and having concerns for the general welfare concern for employees.
iii. Control Variables
From the literature review, control variables are variables used in research to isolate their effect from the independent and dependent variables relationship. Most researchers in the literature have controlled in their CSR methodology, Research, and Development (R and D), Industry type, Company size, age, and leverage.
iv. Financial Performance
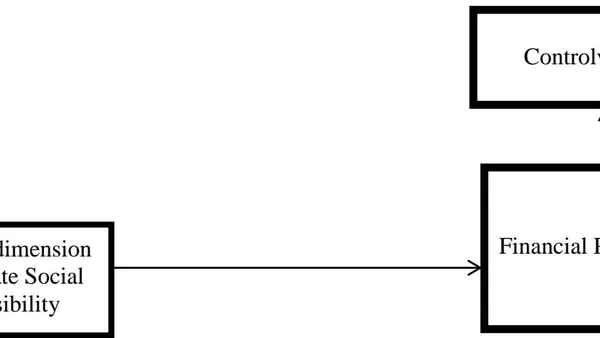
Financial performance (FP) measures how well a company has used assets from its primary mode of business to generate revenue. Cochran and Wood (1984), as cited by Boaventura, Da Silva and, De-Mello (2012), noted that the definition of FP is not debated in the literature, but that there is disagreement concerning the best way to measure FP such as market-based measures (Share Price, Price to Earnings Ratio, Market Share, Dividend Payout Ratio) and accounting based measures (Return on Assets, Return on Equity, Earnings per Share, Return on Investment). Boaventura, Da Silva and, De-Mello, (2012) observed that return on assets (ROA) is rated highest in the frequency of use in empirical research to measure FP. Many strategies and diversities in workforce combination must be harnessed to enhance and sustain financial performance for the well-being of a corporation. Financial performance might be affected by corporate responsibility (CR) to employee. The conceptual framework diagram is contained in Figure 1.
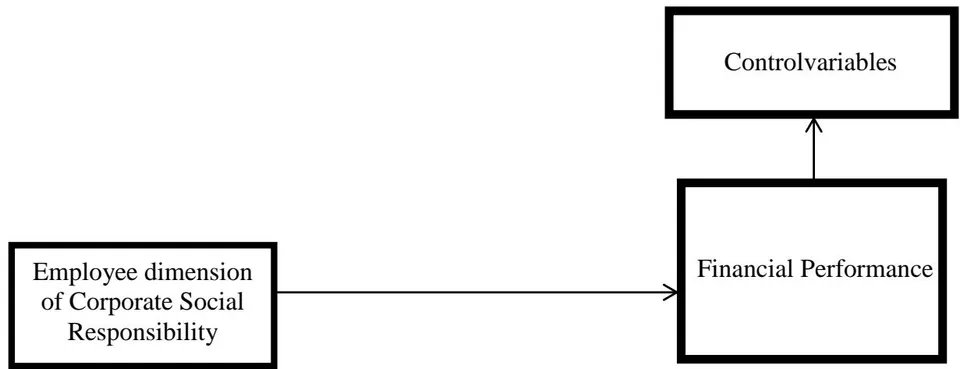
Source: Researcher's Conceptualization (2022)
The employee dimension of Corporate Social Responsibility is the independent variable. The company's efforts toward employees by providing safe working conditions, training employees and, the general welfare concern of employees might enhance the commitment level of employees, resulting in to increase in the rate of retention of employees. An increase in the commitment level of employees would result in operational effectiveness of employees, which could lead to good quality products. Moreover, an increase retention level means a reduction in the cost of recruitment of new employees. These are hypothesized to have an effect on financial performance. Employee dimension of Corporate Social Responsibility is the independent variable in Figure 1.
Financial performance is the dependent variable, which is hypothesized to be explained by CSR to employees as indicated in the Figure 1.
b) Theoretical Framework
Although several different theories have been used to explain the association between corporate social responsibility (CSR) and financial performance (FP), Suttipun and Stanton (2012) noted that the most embracing theoretical perspective in the environmental accounting literature, which explains corporate motivations for reporting, is based on Legitimacy and Stakeholder theories. Tilling, (n. d) stated that Legitimacy Theory has become one of the most cited theories within the social and environmental accounting area. However, there remains deep skepticism among many researchers that it offers any real insight into the voluntary disclosure of corporations. This research concerns the interplay between a corporation and its stakeholders and how the corporation can affect and is affected by these stakeholders. Accordingly, this research is anchored on stakeholder theory.
c) Stakeholder Theory
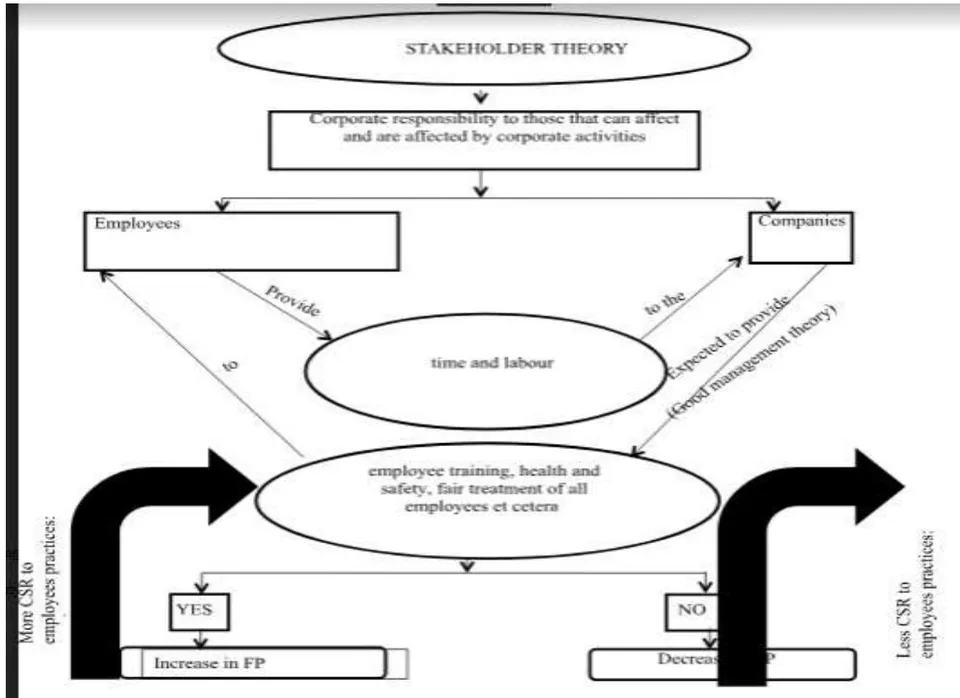
This theory, propounded by Freeman (1984) asserts that organizations have accountability toward a broad range of stakeholders. Matten, (2003) in Hashimu and Ango (2012) opined that Stakeholder Theory is considered a necessary process in the operationalization of corporate social responsibility as a complementary rather than conflicting body of literature. The term, 'stakeholders' refer to groups of constituents who have legitimate claims on the firm (Freeman, 1984; Pearce, 1982; in Hills & Jones, 1992). According to Hills and Jones (1992), legitimacy is established through the existence of an exchange relationship and, stakeholders include: stockholders, creditors, managers, employees, customers, suppliers, local communities, and the general public. Following March and Simon (1958) as cited by Hills and Jones (1992), each of these groups can be seen as supplying the firm with critical resources (contributions), and in exchange, each expects its interests to be satisfied (inducements). Stockholders provide the firm with capital, and in exchange they expect the firm to maximize the risk-adjusted returns on their investments. Moreover, all stakeholders have right to be treated fairly by organizations and corporate social responsibility helps in strengthening stakeholders' relations. There are two broad arms of stakeholder theory: Good Management Theory and Slack Resource Theory. These two theories look at the direction of the causal relationship between CSR and FP. While Slack Resource Theory states that CSR depends on FP, Good Management Theory states that FP depends on CSR. Given the peculiarity of this research, "Effect of Employee Dimension of Corporate Social Responsibility on Financial Performance of Listed Consumer Goods Companies in Nigeria; it is anchored on Stakeholder Theory as we assess the reciprocal effect of CSR on employees (a stakeholder) in affecting FP. Moreover, FP is the dependent variable while CSR to employees is the independent variable, and as such, the study is anchored specifically on Good Management Theory as contained in Figure2.
d) Empirical Review
Doutimiareye (2022) studied "Corporate Social Responsibility and Financial Performance of Listed Consumer Goods Firms in Nigeria." The researcher adopted an ex post facto research design, and the CSR dimensions surveyed were community development cost and employee training cost. The researcher found adverse and significant effects of these CSR costs on FP as measured by ROE. Here, CSR to employees was restricted to employee training cost, but CSR to employees is more encompassing than only looking at the monetary value of it.
Gugong and Ayuba (2018) examined "Corporate Social Responsibility and Financial Performance of Listed Consumer Goods Firms in Nigeria." The researchers applied the correlational research design and CSR was measured using expenditures of the CSR dimensions (community and employees) studied while FP was measured using ROE. The findings, are negative and significant effects of expenditures on CSR dimensions (community and employees) on FP. CSR to employees was only limited to spending on CSR to employees.
Pan, Sha, Zhang, and Ke (2014) conducted a study on, the "Relationship between Corporate Social Responsibility and Financial Performance in the Mineral Industry: Evidence from Chinese Mineral Firms' using panel data for 228 listed Chinese mineral listed firms from 2010 to 2013 with Pooled Least Squares regression analysis. They found different effects of each sublevel CSR issue on FP. Overall, shareholders, employees' responsibilities, environmental responsiveness, suppliers, customers, and consumers' obligations have significant impacts on FP, which are the stakeholders who have the closest linkage with firm operations. In contrast, public accountability outside the firm does not show significant interaction with FP. This study was on listed firms in China.
Albahussain (2015) applied Correlation and the T-Test on, "A suggested conceptual agenda for market orientation and corporate social responsibility towards the business performance of Saudi Industrial organizations," and among other findings, he found a statistically significant positive relationship among all the CSR (customers, employees, community, shareholders, suppliers, and environment) initiatives and financial performance.
Usman and Amran (2015) studied corporate social responsibility practice and corporate financial performance: evidence from Nigerian companies with a focus on the nature and trend of corporate social responsibility (CSR) practices and the relationship between the dimensions of CSR disclosures and corporate financial performance (CFP) among Nigerian listed companies. Content and regression analysis were used respectively to extract CSR and financial data from annual reports of 68 companies listed on the Nigeria
Stock Exchange and to examine the association between corporate social responsibility and corporate financial performance. The results show that the listed companies used CSR initiatives to communicate social performance to their stakeholders and that community involvement, disclosure, product and customer disclosures, and human resource disclosures were found to enhance CFP. The results also revealed a negative relationship between environmental disclosure and CFP, which indicates that disclosure of ecological impact information could be value-destroying in Nigeria. This study was on all listed companies in Nigeria.
Aggarwal (2013) applied Multiple Regression analysis to research "Impact of Sustainability Performance of Company on its financial performance: A Study of Listed Indian Companies". The researcher used secondary sources of data collection, i.e., corporate annual reports for the accounting-based performance measures of ROA, ROE, ROCE, PBT, and GTA and CSR hub database for corporate sustainability measures of governance, communities, employees, and environment rating data and among other findings, the research found that Overall Sustainability Ratings (OSR) has positive but insignificant impact on the financial performance of a company; community-related performance has positive and insignificant effect on the company's financial performance; employee-related performance has negative and significant effect on financial performance; environment-related performance has negative and significant effect on the company's financial performance; and governance-related performance has positive and significant effect on the company's financial performance.
Kaskeen (2017) examined Corporate Social Responsibility and Corporate Financial Performance: Case Study of Pakistan, and among other findings, the researcher found that employee relations had a positive effect on ROA.
Among researchers that found no link between CSR and FP are: Iqbal et al., (2012) in Enahoro, Akinyomi, and Olutoye (2013). They used secondary data, Correlation, and Regression Analysis to examine the impact of corporate social responsibility on the financial performance of corporations in Pakistan. As proxies, they used return on assets and return on equity for financial performance on the one hand and CSR; they used business ethical principles, corporate governance, environmental compliance, social compliance, disclosure of environmental and social report, product integrity, and corporate giving and community investment. They found that CSR does not affect financial performance.
III. RESEARCH METHOD
The descriptive and causal research designs were found appropriate. The population comprised twenty-eight (28) consumer goods companies that were listed on the Nigerian Stock Exchange as of 2019. The entire population was used as a sample; nonetheless, due to insufficient data from some of the listed consumer goods companies (CGC), the sample was reduced to 17 companies using a filter. The data was retrieved from a secondary source: CSR to employee, control variables and financial performance. Data for CSR to the employee was collected using CSR checklist (See appendix B). The CSR checklist was adopted from Jitaree (2015). The annual report of each CGC was perused using content analysis for each practice (item) in the checklist for measurement accordingly. The total CSR to employee index or score for each company for each year was the ratio of the total score obtained to the total score (16) attainable and accordingly computed for the CSR to the employee. This index ranges from 0 to 1.
where,
Corporate social responsibility to employee index of thefirm, where.
Total number of CSR to the employees' items for the firm, ,
if the item was disclosed,
0 if theith item was not disclosed
So that
Data for financial performance was measured using one accounting-based measure of ROA, which has the highest frequency as a proxy used in the past to measure financial performance in studies on corporate social responsibility and financial performance relationship (Boaventura, Da Silva & De-Mello, 2012).
The formula for financial performance is,
Where, ROA=return on assets = dependent variable = Financial performance
Data for proxies of control variables (age of the firm, leverage, and company Size) were obtained from the annual reports. The data needed for control variables were: age (number of years since listed on the Nigerian Stock Exchange); leverage (total debt and equity capital); for company size (logarithm of total assets). In this study, sequence charts of bar charts and the parametric inferential statistics of multiple regressions were found more appropriate to depict the trend in the independent and dependent variables and to test the study's hypothesis respectively. The panel data procedure for regression analysis was adhered to, because multiple regressions conducted without having subjected the data to some diagnostic tests may lead to invalid results. Moreover, the choice of the regression model was robust pls (common effect).
a) Model Specification for Multiple Regressions
Where, i= company 1 to 17, t= the year 2009 to 2019 = 11 years, CSRemplit = Corporate Social Responsibility to employee for company 1 to 17 over 11 years, ROAit = Return on Assets for company 1 to 17 over 11 years, αit = autonomous change in the dependent variable that is not explained by the independent variable for company 1 to 17 over 11 years, β= the proportionate change in the dependent variable arising from a unit change in the independent variable, AGit = Age of the firm = the first control variable for company 1 to 17 over 11 years, LEit = Leverage = the second control variable for company 1 to 17 over 11 years, CZit = Company Size = the third control variable for company 1 to 17 over 11 years, εit = assumed error magnitude of the predictive variable(s) in explaining the criterion variable or the error term that accounts for other factors affecting the dynamics of the dependent variable not captured in the model for company 1 to 17 over 11 years.
b) Decision Rule
-value: we reject the null hypothesis, if the p-value is less than ( ) otherwise, we do not accept the null hypothesis. Alternatively, at a significance level, we reject the null hypothesis if otherwise we accept the null hypothesis.
The data was restricted to secondary data, which was extracted from annual reports and accounts of 17 listed consumer goods companies in Nigeria. The study covered a period of eleven years (2009-2019) yielding for the research, 187 observations, that is, 17 x 11.
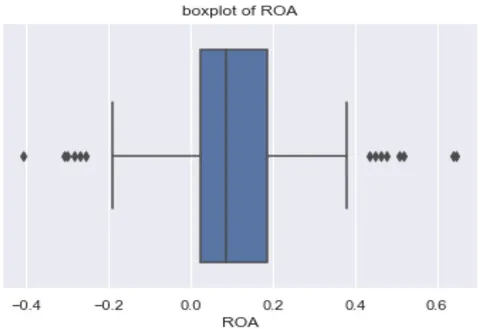
Data was scrutinized for missing values, but all the expected observations per constructs were intact. Followed by, was the detection of outliers. Outliers were detected in constructs (ROA, CSRempl, AG, LE, and CZ), (see Figure 3 below for outliers in ROA). Outliers were removed using the outlier removal code: new_y=@recode((y>@quantile(y,0.95))+y<@quantile(y,0.05)),NA,y). Also, to get rid of NA (not available) or to retain the total number of observations in the sample data, AsifAhsan@which is the best method to remove outliers in a data [email protected] states that a straight forward way to remove outliers is first to identify the outlying observations and replace them with the median value. The researcher thus obtained the median values in the descriptive statistics for those data sets plagued with outliers and applied the
modifiedoutlier removal code to new_y @decode((y quantile(y,0.95)) + (y quantile (y,0.05)),median,y)
Figure 3 below shows outliers in return on assets (ROA)
IV. SEQUENCE CHARTS ANALYSIS OF DATA
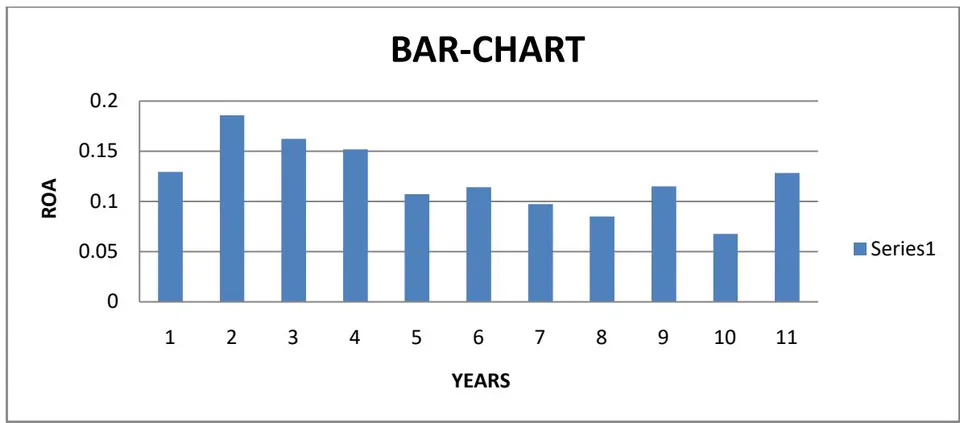
a) Bar Chart of ROA
This shows the trend in return on assets (ROA)
b) Bar Chart of CSRempl
This shows the trend in Corporate Social Responsibility to the employees (CSRempl)
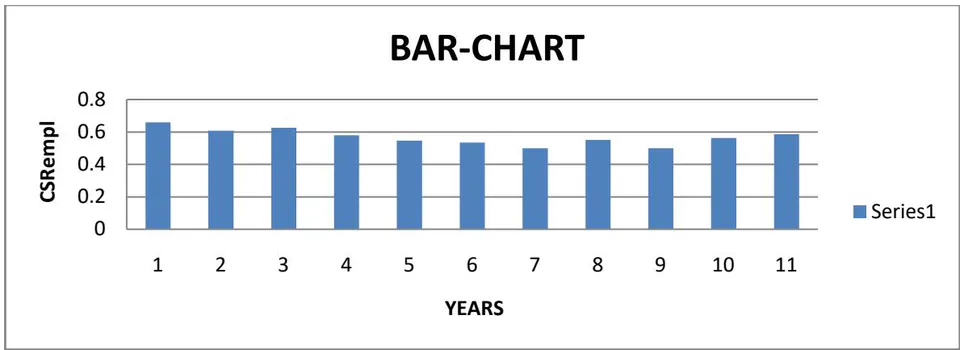
Source: Researcher's Computation from Data using Python Programming Language (2022) In the Figure 5, CSRempl was highest in 2009, followed by 2011, 2019, 2009, and 2018, and lowest in 2017 and 2015.
V. RESULTS AND DISCUSSION OF FINDINGS
| EFFECT | RANDOM | FIXED | COMMON | ROBUST OLS | ||||
| VARIABLE | COEF. | PROB. | COEF. | PROB. | COEF. | PROB. | COEF. | PROB. |
| C | 0.458562 | 0.0611 | 0.436000 | 0.1306 | 0.546902 | 0.0286 | 0.479788 | 0.0488 |
| CSREML | 0.099788 | 0.3372 | 0.073944 | 0.5826 | 0.232878 | 0.0259 | 0.267168 | 0.0087 |
| AG | -0.003277 | 0.0133 | -0.008551 | 0.0329 | -0.004194 | 0.0002 | -0.004604 | 0.0000 |
| LE | 0.040776 | 0.3104 | -0.007149 | 0.8732 | 0.107557 | 0.0140 | 0.092173 | 0.0300 |
| CZ | -0.056332 | 0.0881 | -0.015768 | 0.7289 | -0.072086 | 0.0313 | -0.058578 | 0.0728 |
| R2 | 0.142033 | 0.575509 | 0.238182 | 0.252857 | ||||
| R2 Adjusted | 0.056237 | 0.450659 | 0.162000 | 0.178143 | ||||
| F-Statistics | 1.655466 | 0.122437 | 4.609600 | 0.000001 | 3.126498 | 0.003988 | 33.45147 | 0.000051 |
The effect of CSR on employees is positive and significant. That is, a unit increases in CSRempl results in a 0.27 increase in ROA.
| Hypothesis | Regression model | Results | Results in agreement with that/those of | Results in disagreement with that/those of |
| Effect of CSR to employee | robust pls (common effect) results | Positive and significant | Pan et al., (2014),Albahussain (2015),Usman and Amran (2015), Aggarwal (2013) negative and significant, Doutimiareye (2022) significant but negative, Gugong and Ayuba (2018) | Iqbal, et al, (2012) in Enahoro et al., (2013) |
The effect of CSR on employees is positive and significant. This finding agrees with those of Pan et al. (2014), Albahussain (2015), Usman and Amran (2015), Aggarwal (2013) significant but negative, Doutimiareye
0.27 increase in ROA. This finding is by, following, per, under the theoretical expectation that an increase in CSR on employee relations would lead to an increase in financial performance. The implication of this finding is that increase in CSR to employee (complying with health and safety standards and regulations, providing information on education/training of employees on health and safety, providing information on accident statistics, providing low cost health care to employees, employees training/giving financial assistance to employees in educational institutions or continuing education courses, providing recreational activities/facilities, providing staff accommodation/staff home ownership schemes, food, fuel, other benefits, information about support for day-care, maternity and paternity leave, holidays and vacations, disclosing policy for company's remuneration package/schemes, providing information of employees share purchase scheme, providing information on number of employees in the company/branch/subsidiary, providing information on qualifications and experience of employees recruited, providing information on the stability of the workers' job and company's future, reporting on company's relationship with trade unions/workers and providing information on recruitment/employment of minorities /women/special interest groups) would result to an increase in financial performance.
VI. CONCLUSION
The results of the study are determined by the validity of information collected via the CSR checklist and by extraction from annual reports and accounts of listed consumer goods companies in Nigeria. Research of this nature with increased sample size and or covering more years should be conducted on listed consumer goods companies in Nigeria. Moreover, there are other dimensions of CSR, including the latest one (COVID-19) that warrant their effects on financial performance to be researched. The paper recommends that listed consumer goods companies should do more on corporate social responsibility on employees to improve workers' motivation and corporate reputation and image that can potentially improve financial performance.