I. INTRODUCTION
The Information revolution has changed the everyday life of people in the 21st century. New technologies such as artificial intelligence, cloud computing, robotics, 3D printing, the Internet of Things, and advanced wireless technologies, among others, have changed the way companies operate. The development of Information technology (IT) has inevitably brought changes in the functioning of the banking sector. The Internet has enabled banks to conduct transactions automatically, from any place and at anytime. Banks provided their services more efficiently and at substantially lower costs. Banking transactions combined with the Internet, known as Electronic banking (E-banking), have provided banks with a comparative advantage in terms of time, location and costs. Some authors classify E-banking as Internet banking and Mobile banking. Internet banking means that banking transactions are realized through a computer or laptop, and mobile banking performs those transactions through mobile phones applications. The development of E-banking has overshadowed the use of traditional banking which is based on direct, physical contact of customers with employees in the so-called "brick and mortar" branches of the bank.
In 2020, the world was shaken by the health crisis caused by Covid-19 virus. The Covid-19 has changed the way people live, interact and make purchase decisions. This pandemic further stimulated the development of E-banking. The use of traditional banking worldwide has declined dramatically during the health crisis. People around the world have faced quarantines, closures of companies and institutions, and health institutions have given recommendations "to stay home" and carry out all purchases from home. Under pressure from Covid-19, people had no choice but to use electronic banking. The pandemic has further encouraged the use of E-banking.
However, the success of E-banking depends on the understanding of the key factors that determine customer satisfaction and service quality. The correlation between the bank offers and the customers' needs and wants becomes more critical in view of the increased competition in the banking sector. The challenge for banks is not only becoming just "digital", but also providing value that customers are comfortable paying for. Thus, banks are trying to transform their strategies that define their future and to rethink their entire flow of activities. These involve not only the digitalization and modernization of financial processes of the banks, but also the development of skills and the promotion of a sustainable bank-customer relationship.
Based on these trends, the paper will attempt to answer the following research questions:
What are the strengths and weaknesses that Macedonian commercial banks and their customers face in the modern digital environment?
What are the opportunities and threats to the banking sector and to the customers from the digitalization process?
Which are the further recommendations for the E-banking development in the Republic of North Macedonia?
These research questions will be answered with the help of two questionnaires that have been electronically distributed to Macedonian commercial banks as well as to their customers.
II. LITERATURE REVIEW
Banking is the backbone of any national economy. The development of banking speaks for the economic development of a country. The more developed the banking, the more developed the country is.
Banking, thanks to the Information revolution, is further developed in the direction of using new electronic tools for service delivery. The combination of banking and the Internet has led to the development of E-banking. Hertzum et al. (2004) defines E-banking as web-based banking. In other words, E-banking refers to the banking operations, which is done over World Wide Web. According to Keviani (2007), "Electronic banking is an umbrella term for the process by which a customer may perform banking transactions electronically without visiting a brick-and-mortar institution." The following terms all refer to one form or another of electronic banking: personal computer (PC) banking, Internet banking, virtual banking, online banking, home banking, remote electronic banking, and phone banking. However, more comprehensive and well-established definition is given by the United Nations Conference on Trade and Development (UNCTAD). This definition covers almost all area of E-banking: "Internet banking refers to the deployment over the Internet of retail and wholesale banking services. It involves individual and corporate customers, and includes bank transfers, payments and settlements, documentary collections and credits, corporate and household lending, card business and the like."
For consumers, E-banking provides current information, 24-hours-a-day access to banking services. E-banking is very helpful for the customers and for the banks in overcoming the drawbacks of manual systems as computers are highly capable of storing, analyzing, consolidating, searching and presenting the data with a lot of speed and accuracy. The primary services provided by e-banks are transferring money among one's own accounts, paying bills, and checking account balances. Loans, brokerage, proprietary trading, service bundling, and a host of other financial services are being added to these primary services (Dewan & Seidmann, 2001). The range of banking products offered online is increasing due to the sophisticated needs and wants of customers.
Banks, like other companies, must listen to the "voice of the consumer" in order to survive in the market. The banking expert J.P Nicols (2015) always reminds banks that "they have to upgrade themselves or risk being burnt to the ground". E-banking is fast becoming a strategic necessity for most commercial banks, as competition increases and becomes more severe. Some specific factors that have conspired to create the new competitive environment for banking include: changing consumer needs and perceptions, globalization, technological innovations, and competition from non-banking entities (Mishra, 2001).
Consumers are increasingly looking for services they can access from a single entry point. Seitz (1998) noted that consumer behavior in banking changed partly as a result of changes in the amount of spare time available to individuals. Mobility, independence of time and place, and flexibility have become key words in consumer banking. Moreover, today their behavior is changed due to their advanced technological knowledge and skills and the pandemic that has affected the whole world in 2020. Consumers, are quickly adapting to new banking transaction delivery systems, which are easier, cheaper and less time-consuming.
E-banking is widely used in every country in the world. Regarding the situation in the North Macedonia, according to Vice Governor Kadievka, "the digital revolution in the past thirty years has brought significant changes in all spheres of economic activity, including the banking industry in Macedonia. Analyzes show that the banking sector tends to keep pace with modern technological trends, with the trends of increasing accessibility of the population to the Internet, the growing use of smartphones and, accordingly, with the changing consumer culture of the population. However, there are factors that limit the digitization of financial services. She mentions the following factors:
- Population distrust in E-banking services (especially the elderly population);
- Insufficient information and education of the citizens about the benefits of the E-banking, such as saving time, saving efforts, less financial costs, etc.,
- Resistance to change - high percentage of customers that use of bank counters for raising money and depositing of cash,
- Lack of competition in the domestic economy, such as lack of fin-tech and low-representation of other non-banking institutions that would compete with the banks.
Factors that contribute to the digitalization of financial services are:
Increased internet distribution in the country – statistics show that of households had access to broadband Internet, and the same percentage of them use the Internet,
High degree of financial inclusion (access to bank accounts)
High degree of mobile telephony coverage (over 2 million SIM cards in circulation, with Internet) and
The gradual breakthrough of non-banking institutions and increase of the competition (Telecom, PayNet, PayPal).
What is really happening today in banking institutions and what is the opinion of the customers about the digitalization of banking services can be analyzed in more detail from the distributed questionnaires.
III. RESEARCH METHODOLOGY
For the purpose of this paper, two sources of data were used:
Secondary data: data and information from relevant existing literature on E-banking, like journals, statistical data, reviews, e-books, published presentations, blogs and expert's published views. Mainly online sources were used. E-banking is a very popular and modern topic and the Internet abounds with numerous articles, reviews, considerations about its use, its advantages and disadvantages. The paper uses a number of published publications and works on E-banking by domestic and foreign authors.
Primary data: Two questionnaires, one regarding the E-banking implementation and development in the Macedonian banks and the other related to the
IV. DISCUSSION AND ANALYTICS
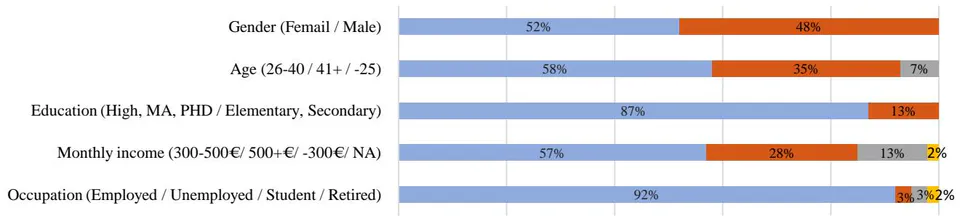
Macedonian banking sector is characterized with a low degree of financial intermediation, high capitalization, and a high share of foreign capital in the ownership structure. There are only twelve commercial banks and one national development bank. Households dominate in the credit and loans structure of the Macedonian banks thus the focus in the research is given to them. The demographic characteristics that show the respondents profile, from the aspect of highest percentage of E-banking usage from gender, age, education, monthly income, and occupation perspective are presented below in Figure 1.
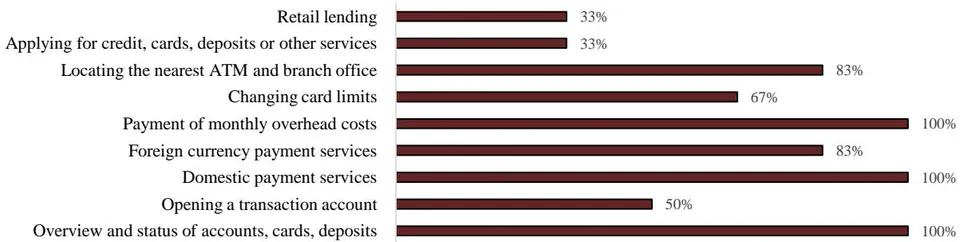
Banks in the Republic of North Macedonia follow the new trends in digital banking in order to maintain their competitiveness on the banking market. In order to determine the level of digitalization of banks' products and services, banks were asked to identify the level of their web page and whether they have incorporated E-banking services. According to the results, of Macedonian banks have their website with informational character enriched with interactive activities (e.g. credit calculator, credit card application etc.), including e-financial (overhead) transactions and with fully transactional - e-payments in domestic and foreign currency payment operations. One bank has its web page enriched with applicative usage of electronic products and services (e-lending, insurance policies, account opening, deposit, etc.). Hence, only one bank has its web page operational on a level of information enriched with e-payments and other e-financial (overhead) transactions, but only in domestic payment operations. Regarding incorporation of E-banking services, all banks answered that they are already engaged in offering E-banking. However, not all of the banking services offered via bank branches are incorporated in the E-banking system. In banks' responses regarding which of the services offered through their branches are available on the E-banking platform, none of the banks offer corporate lending, investment services (asset management, trading-securities), financial support (financial/investment advice) and Bank assurance in the form of E-banking
services. As shown in Figure 2, only of respondents offer retail lending and applying for credit/debit cards, offer opening a transaction account, offer changing debit/credit card limits and offer location of the nearest ATM and branch office and foreign currency payments.
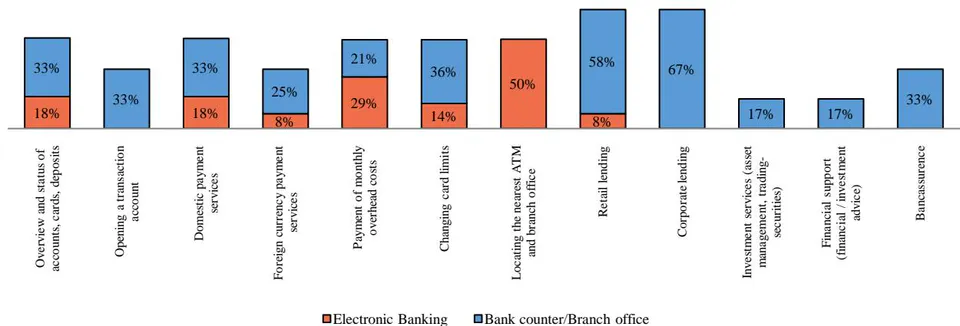
From banks' point of view and when analyzing their records regarding customer's preference on how to use banking services, responded that they prefer the usage of bank branches more, whereas answered that they favor the usage of E-banking services. For the purpose of determining which are those services that customers prefer more to conduct them online or through the bank branch, the results (see Figure 3) show that customers in almost each offered service, except for payment of monthly overhead costs and locator of ATMs and bank branches, choose more to visit the "brick and mortar" bank instead of using the E-banking.
When customers were asked "How do you use the banking services?" answered by E-banking, via telephone, were using personal banker, by ATMs and by bank branches. Furthermore, when customers were asked which banking services they used mostly online (see Figure 4), answered that they often use E-banking services for informative purpose such as overview and checking the status of their accounts, cards and deposits; of the respondents use it for domestic payment services, and for payment of overhead costs.
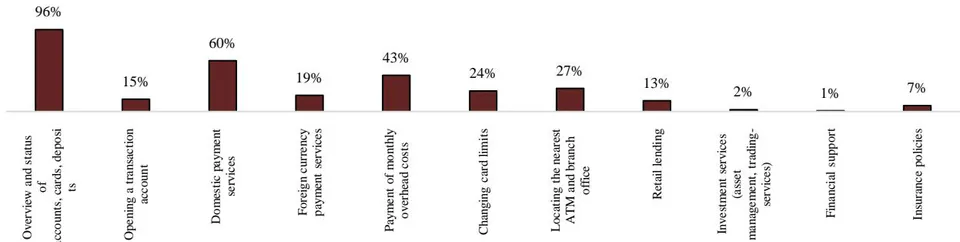
This is a reminder that even though Macedonian banking sector is trying to keep pace with the latest trends in digital transformation, it still has the essential characteristics of the traditional commercial banking system, i.e. where the bank branches are the central unit around which banks operate.
In order to determine the significance that E-banking has for customers in daily life, responded that E-banking has significant usage in their daily lives, responded that their usage of E-banking is neither insignificant nor significant and only answered that their usage is insignificant. Additionally, of the customers-respondents are satisfied, extremely satisfied, are neither satisfied nor satisfied, and are unsatisfied with the use of E-banking services. On average, they are satisfied with E-banking services (4.05) and this, together with the significance that they impose, should be a signal to banks to start investing in E-banking today, more aggressively and without hesitations. Customers are satisfied at the moment, but their needs and desires are sophisticated and need to be met in future as well. Only satisfied customers can keep the banks alive. From the above discussion, it can be concluded that customers are "left" on the banks' strategies and their capacity for introducing new or transforming the existing products through E-banking.
Banks were also asked about their perception of the level of digitalization and their future engagement in Fintech innovation. of the banks answered that they are close to greater digitalization in operations, and only would engage in Fintech innovation only as a long term commitment. Even though E-banking is highly significant for the customers, from the results it is obvious that Macedonian customers should wait for conducting more sophisticated E-banking services for a longer period of 3 to 5 years.
Exploring deeper the effects of E-banking, two sided - SWOT analysis, i.e. positive changes and new opportunities on the one hand, and challenges and threats on the other, for both banks and their customers, of the application of E-banking is furtherly elaborated in detail.
Internal positive changes or strengths: Firstly, the gains from the increased banking efficiency would be discussed because the digitalization is followed by qualitative improvements of the existing banking services and creation of constantly new products. From this point of view, the benefits of the development of e-products and e-services in the banking business can be summarized primarily in: a) the possibility of presence everywhere; b) faster and greater access to new types of banking transactions; c) increasing ability to consolidate financial operations and improve overall efficiency; d) drastic reduction of transaction costs; e) increased competitiveness, flexibility and responsibility to customers. E-banking has the potential to accelerate existing trends and introduce new ways of doing business, organizing work and networking in society. Lower transaction costs, network effects created by increased returns and larger economies of scale, can be achieved through the use of e-services online. In this context, banks were asked about the benefits that E-banking and the usage of advanced technology has, by assigning a degree of agreement (on a Likert scale from 1 to 5) on a several statements. Answers were the following: on average, banks strongly agree with the quick and efficient communication with customers (5.0); partially agree that it brings improved services (4.67), development of new banking products and services (4.83), increasing market share and expanding in new markets (4.0), improving the risk management process - new models and databases (4.0), greater security of information systems (4.0) and increased competition (4.3). However, banks are neutral when asked whether they agree that E-banking leads to reduction in the number of bank branches. Furthermore, when banks were asked to assign how they feel about the introduction of E-banking, their answers on average were that they highly agree with the intensity towards extremely high agree (4.67) with the posed statement that "E-banking is a necessity in the new digital economy". According to the above stated findings, Macedonian banks are aware of the advantages that E-banking offers, and they acknowledged its significance, but not in a full scale.
The strengths from E-banking usage for customers are mainly related to: a) opportunity and possibility for payment from anywhere in the world; b) improved quality of services; c) personalized banking products and services; d) rapid response; e) low fees and commissions; f) new banking e-products and e-services. Namely, the advantage of E-banking is that before the transaction is even completed in the traditional way, by posting the necessary information in an available form online, customers are a priori in a position to know which financial product they want and can use. Therefore, when customers asked about the most important reasons for using E-banking services, their answers were: there is no waiting queue (88%), the transaction time is shorter (75%), the execution of transactions is easier (72%), E-banking responds to my needs (66%), and the transactions are cheaper (49%). Furthermore, in order to determine the benefits, they have from the usage of E-banking services, customers were asked to assign a degree of agreement (from 1 to 5) of a certain statement. On average, they agree that E-banking offers shorter transaction times (4.2), that E-banking is easy to use (4.0) and that E-banking corresponds with their needs (3.97). However, they are neutral toward high intensity of agreeing that E-banking is cheaper (3.8). When customers were asked about what they would change in their banks' offer in a free answer, more than 5% filled in that the use of E-banking services is not very cheap. However, when analyzing banks' responses related to this area, and by looking at their price lists, conducting e-payments is 4-5 times cheaper than conducting payments in a bank branch. In conclusion, customers have the perception that E-banking is not cheaper, due to the obligation to pay certain fees for using E-banking.
Weaknesses: There are several challenges that banks need to overcome in order to take full advantage of E-banking. In addition to non-proprietary standards and the open nature of electronic operations that will lead towards increased transparency and competition (positive effects), it will also lead to potential threats to privacy (adverse effects). Limitations or shortcomings of E-banking can be identified as:
Overflow of information syndrome, where customers, may be confused and to not know how to work and research with an obvious definite list of information services;
Need for certain new costs for physical installation and maintenance of the new IT (websites, hardware, software programs), meaning that the entry fee can be quite high, not only in terms of capital costs required to introduce the technology, but also in terms of understanding the technology, especially how to make full use of it;
Restraint in the application of web-based strategies due to the observed "uncertainty" about the use of the Internet as a business environment and as a basis for contact. The basic business needs and goals in banking are for transactions to be private, secured, guaranteed and timely. Not all of them can be filled with online E-banking. Fintech products are
sensitive to external attacks. Without adequate collateral technology in banking, incalculable financial damage (high operating risks) as well as damage to its reputation (high reputation risk) may arise. Therefore, while the new IT may drastically reduce some transactional and distribution costs, new costs associated with building trust and reducing risks will arise.
- E-banking reduces the volume of face-to-face meetings, which may further lead to downsizing of the customer base. Given that preferences for an alternative variant of the product are often explained more easily using gestures and intonations than by grammatical sentences, we can really argue that E-banking has its limitations. When transactions are performed online, customers are faced with asymmetric information, with inability to physically verify the information being exchanged. By making the information in a richer electronic (digital) form, an attempt is made to overcome the problem with the asymmetric information. However, Internet information very often has a commercial motivation and value, thus the accuracy of such information is often questioned.
When analyzing the degree of difficulties or weaknesses that banks face when performing E-banking activities (on a scale of 1-extremely low to 5-extremely high) it can be concluded that on average the endured difficulties are with very low intensity to neutral, where as the highest average value is noted on high costs for development, in which of the banks answered that they faced high degree of problems when applying E-banking (see Figure 5).
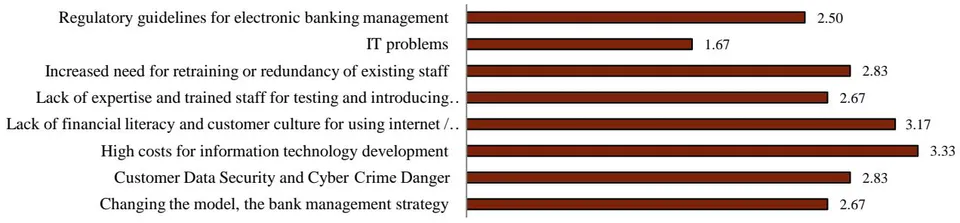
Having in mind that the introduction and implementation of E-banking asks for radical changes in the organizational infrastructure and imposes weaknesses in the area of human resources, banks were asked whether they have a special team for introducing and monitoring E-banking and if yes, whether the team for introduction and monitoring of E-banking is organized as a working group, division or as a department. The results show that all of the banks have a special team for introducing and monitoring E banking, but organized it as a working group, as a division, while organized it as a separate department. Secondly, they were asked to assign a degree of impact (on a scale of 1 to 5) and the direction of impact of the introduction of E- banking on the number of employees. As analyzed, E-banking on average has low impact on the reduction (1.83), increase (2.50) and in the requalification of the workforce (2.33).
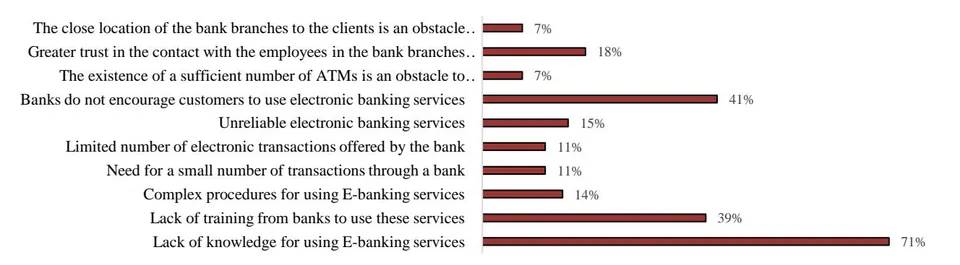
When analyzing the limitations that come with the application of E-banking, from the customers' point of view, it can be noted that customers on average do not agree: that the best is the direct contact with the employees in bank branches (2.20), that they prefer banking services directly from the bank branches (2.0), that the use of E-banking is complex (1.80) and that using E-banking is unsafe (1.98). Regarding the question on the barriers of using E-banking, most respondents (71%) believe that lack of knowledge about E-banking services is the biggest obstacle. Many respondents cited the lack of training by banks as an obstacle, as well as the fact that banks do not encourage users to make greater use of E-banking (see Figure 6). It can be concluded that consumers' have needs for additional education and training about E-banking.
Asking the banks, whether they educate their customers on E-banking, their responses were as follows: of the banks educate their customers through trainings organized by the bank (own staff), and all of them educate their customers through their branches - in communication with employees, and through tutorials available on the website/mobile application. When banks were asked how they provide additional education and/or training to employees in the field of E-banking, answered that they conduct internal training in the bank, and per respectfully at the level of the group to which the bank belongs, and by seminars where lecturers are experts from other institutions.
Opportunities: The only thing that today's customers want is added value of the product and services, they receive. The digital transformation enables implementing new business strategies by banks to offer a wider range of financial products, starting with personal finance management, overview of all banking accounts, investment management, advisory services etc., which, in general, means creation of customized customer based products that give additional value to consumers. When analyzing the attitudes that Macedonian banks have for the opportunities that E-banking offers to them, on average they answered that there is a high level of opportunity to offer a greater number of products and services (4.17) and the opportunity to offer products and services with added value, the so-called integrated products (4.20). However, on average, they are neutral when answering about the opportunity for better management of capital and risks (3.20).
On the side of the customers, when asked about what they expect from their banks in the near future, answered that banks should be focused on offering new technological products, while do not expect their bank to offer new technological products and did not respond to this question at all. When asked the customers what they would change anything in E- banking services in a free answer, some of the responds related to this area were the following:
- Expansion of the services offered by the bank through mobile banking,
- Cancellation of the monthly fee for E-banking,
- More information on E-banking services,
- More training for the usage of E-banking,
- Add voice banking for elderly people and
- Shorter and understandable procedures.
Threats: New financial ecosystem is evolving and on a global scale digital service providers, such as Robo consultants, credit card issuers, P2P lenders, insurers, brokers and asset managers are considered as important elements. These companies are already overtaking large shares from the banking market and responding to the changing financial needs of their customers. Macedonian banking sector still lacks the competition from new entrants, such as Fintech companies since a new regulatory framework is needed to be implemented in order to support them. This situation should not be underestimated, having in mind that the regulatory body makes an effort and is already in the process of supporting and developing the Fintech sector that would "shake up" the banking industry. Threats would be noted by the Macedonian banks in the near future in the provision of payment services as well, since the monetary authority is already in the process of rolling out a significant update to the Law related to payment services and payment systems and bringing them in line with the EU's PSD2 Directive, EMD2, PAD, SFD, IFR and some provisions from SEPA Regulation. Regarding the possible threats that arise around the E-banking system, Macedonian banks were asked to rate
the impact (on a scale from 1-extremely low to 5 - extremely high) that the entry of new Fintech institutions into the Macedonian financial market would have (see Figure 7).
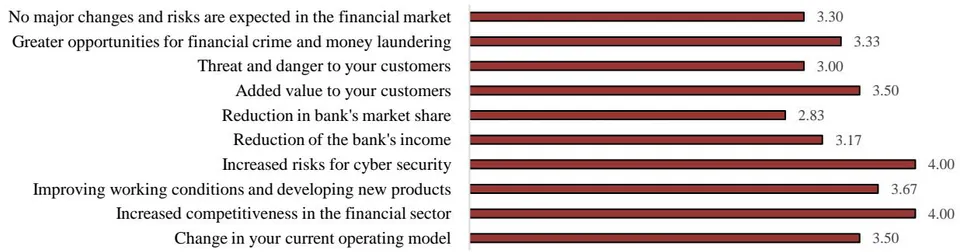
Banks, on average, face high degree of threats in their main areas of functioning regarding increased risks for cyber security (4.0) and increased competitiveness in the financial sector (4.0). Strong capitalization of the Macedonian banks as well as stringent rules for entering into the banking sector are the main reasons why possible reduction in banks' market share is regarded as a low threat for the banks. Nevertheless, threats in the areas of deposit collecting and lending, investment management will come for sure, because they are predetermined elements of any of the possible scenarios (bricks and click or click and click) that will evolve in the future and they will have high influence over the banking businesses.
From customers' point of view, strongly disagree that using E-banking is unsafe and unsecure, disagree with this statement, while neither agree nor disagree, agree and very much agree. On average (1.98) they disagree that E-banking is unsafe and unsecure. Additionally, on average they very much disagree with intensity toward disagreeing with the statement that using E-banking is a complex process (1.80). Hence, more than of Macedonian customers do not feel threaten neither by the cybercrime nor by the complexity of E-banking services, are neutral, of the customers feel threaten by the risk of cyber-crime and complexity of E-banking and have not replied.
Through capital increase, technological change leads to changes in capital and labor, to an increase in capital productivity, which in turn leads to growth and development. In the long run, the combination of new banking products, expanded market research, income gains and reduced fees and commissions because of increased productivity will lead to increased net profits. Namely, in the long run, every bank probably will have more advantages than disadvantages of increased volume and facilitated access to information, products and services. Banks that will be able to be the first in their strategies to apply e-innovations in E-banking according to the needs and requests of the customers, will also be leaders and first beneficiaries of Fintech gains.
V. CONCLUSION AND FURTHER RECOMMENDATIONS
Research data show that Macedonian banks as well as customers are increasingly oriented towards E-banking, which is a stark reality that will expand in the future. of the bank's customers have been using E-banking for quite a long time (one to over 5 years) and with high frequency (80% of the respondents use E-banking services either daily or once/several times a week). Large number of respondents i.e., around use E-banking. Customers currently are satisfied with the e-services offered by banks, but of them still expect greater digitization of banks in the future as well as a more diverse and wider offer of new technological products and services. Customers do not feel threatened by cyber-crime and complexity of E-banking services, but they do feel lack of knowledge and additional training in the area of using the E-banking services.
Today, Macedonian banks are faced with the digital transformation, the Covid-19 pandemic, as well as with fierce competition from Fintech companies and many startups who are entering the banking sector. Banks are forced to continuously transform their business models. To make efforts by using new technologies to innovate and introducing new products and services with added value for the end customer. Finally, it must be understood that every customer counts. The research shows that the number of transactions performed through E-banking is relatively small, and most of the customers use them for informative needs. Macedonian banks are gradually introducing new services in order to bring E-banking closer to the customers and meet their needs. New Fintech products and services as well eventual engagement with new Fintech companies is incorporated mainly in the long term strategy of the Macedonian banks. Having into account the findings, the following recommendations for Macedonian commercial banks can be derived:
- Banks should provide educational programs, tutorials and training to the customers about digital banking!
- Banks should increase investments in the cyber security and, thus reducing this threat, would mean boosting the customers' confidence!
- Banks should adopt in their short term strategies greater digitalization of their operations as well as a more diverse and wide offer of new Fintech products and services according to the needs of their customers!
- Banks must prepare to face increasing competition from the Fintech newcomer and forthcoming payment changes in the Macedonian financial market!
The success and profitability of the banks will be largely determined by their ability and skills to allocate every saved capital in sufficiently flexible multiple financial products and services which will be repeatedly applied with reduced risk level in the decision-making process.