I. INTRODUCTION
Unit root test in econometrics is crucial to determining the nature or order of integration of macroeconomic variables. It is the foundation for most statistical techniques such as error correction models, granger causality, cointegration tests to mention but few applied in economics, business and finance.
A large number of literature exists on this subject. However, most researchers determine macroeconomic variables' order of integration based on regular unit-root tests such as Augmented Dickey-Fuller test, Phillips-Perron (PP) test and other regular tests. This present work involves unit-root tests with allowance for a shift in the intercept of the trend function and slope since most macroeconomic time series are interpreted as stationary around a deterministic trend function. Specifically, the extended Augmented Dickey-Fuller test through innovational outlier and additive outlier models were employed as proposed by Perron (1989, 1997). The significance of these methods is that we are able to establish important breakpoints usually associated with shocks on macroeconomic variables.
II. METHODS AND RESULTS
Three monetary policy variables comprising interest rate (ir) (proxy by Treasury bill rate), inflation rate (inf) and exchange rate (ex). Also, real gross domestic product (rgdp) was used as the measure of the Domestic Output and lastly unemployment rate (um) were involved in the vector autoregressive (VAR) model. Cubic low to high-frequency conversion method was employed on quarterly real gdp and unemployment rate data, without loss of statistical properties (Alabi and Bada, 2018). Furthermore, we transformed the original data into the natural log to ensure that the normality assumptions in the error term in the VAR model can be sustained.
The stationarity of each of the series was analyzed by conducting individual unit-root tests. An extended Augmented Dickey-Fuller test with innovational outlier and additive outlier breakpoints as proposed by Perron (1989, 1997) were employed (Models 1, 2 & 3). According to Zivot & Andrews (1992), Lumsdaine & Papell (1997) & Perron (1989, 1997), if allowance is made for a shift in the intercept of the trend function and slope, most macroeconomic time series are interpreted as stationary around a deterministic trend function. We considered the following three models at levels with dummy variables for different intercepts and slopes. The Model 1 involves including the dummy variable for a change in the intercept of the trend function steadily in a way that relies on the correlation function and the innovation (i.e., noise) function (Perron, 1997). The dummy variables are presumed to be unknown rather than known ex-ante.
where
These models were estimated using the Ordinary Least Squares (OLS). The indicator functions are expressed as , , and . We test the null hypothesis that a=1 using the t-statistic) , where k is the truncation lag parameter which is also unknown. Model 1 and 2 are referred to as the innovative outlier models (i.e., IO1 and IO2) respectively. Model 3 is called the Additive model (i.e., AO) because a rapidly change in the slope is allowed but the two fragments of the trend function are joined at the breakpoint. According to Perron (1989 & 1997), the breakpoint may be chosen such that is minimized. The minimized t-statistic is expressed as:
. The break point was selected in a manner to maximize the t-statistic on the shift in slope. Here, the test statistic for testing the null hypothesis are for model 1 and for models 2 and 3, where is such that and . was selected by allowing this point to correlate with the data as much as possible although with some loss in power. This was done by imposing no restrictions on the sign of the change. The truncation parameter was selected using the t-sig and F-sig general to specific recursive procedures as proposed by Perron (1989). These procedures are particularly better than information criteria such as Akaike Information Criterion and Bayesian Information Criterion due to their size stability and better power (Perron, 1989).
| t-sig | F-sig | ||||||||
| Variable | Model | ADF test@ | k max | k* | Breakpoint | t-statistic | p-value | p-value | Remark |
| um | IO1 | 1st Difference | 12 | 12 | 2016:12 | -4.7523 | ...... | 0.0637 | I(1) |
| rgdp | AO | 1st Difference | 13 | 12 | 2007:07 | -4.6286 | ...... | 0.0132 | I(1) |
| inf | AO | Level | 13 | 13 | 2011:10 | -5.2002 | 0.0177 | ...... | I(0) |
| ir | IO2 | Level | 5 | 1 | 2015:09 | -4.8494 | 0.011 | ...... | I(0) |
| ex | IO1 | Level | 5 | 1 | 2015:12 | -5.0324 | 0.0286 | ...... | I(0) |
Source: Authors personal computation
The results of unit-root test reveal that unemployment rate, and real gdp are stationary of order one under the Innovative Outlier Model 1 and Additive Outlier Model respectively. The truncation lag lengths of were selected using the F-sig approach. The p-value for the real gdp unit-root test is lower than that of the unemployment rate unit-root test. This is an indication that the Additive Outlier Model has more power than the Innovative Outlier Model 1 on these series. The remaining series, i.e. inflation rate, interest rate, and exchange rate are stationary at level under Additive Outlier model, Innovative Outlier Models 2, and 3 respectively. The for inflation rate and for interest rate and exchange rate were chosen using the t-sig recursive technique. The k max was chosen arbitrarily avoiding the problems of multi collinearity amongst the variables and loss of power usually associated with high values of k max. This quantity was 13 lags (for real gdp and inflation rate) and 5 lags (for both interest rate and exchange rate). Only the unemployment rate has a binding k max at 12 lags. The breakpoint dates correspond to significant periods of global economic and Nigerian government policy change shocks. The logarithms of the macroeconomic variables are as shown in Fig. 1 below. The breakpoints are selected to maximize the t-statistics (Table 1).
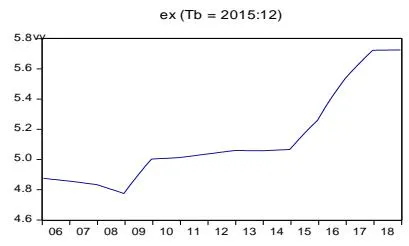
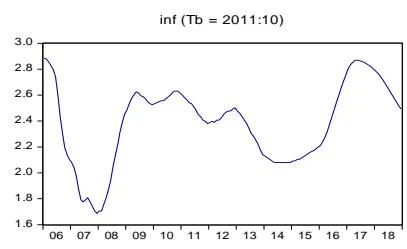
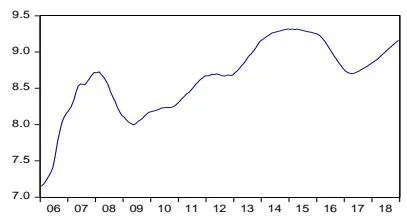
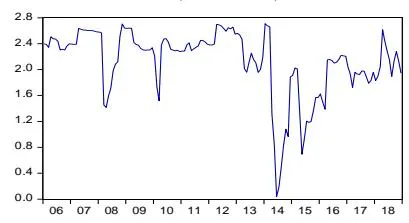
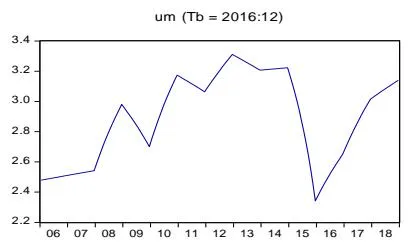
Firstly, there was a global financial crisis in 2007 when major financial institutions in the United States collapsed. The effect of the global financial crash was observed in Nigeria's real gdp in July of 2007. Secondly, Nigeria is known for its inflation targeting monetary policy. Under this policy, the Central Bank of Nigeria (CBN) uses the monetary policy rate (MPR) and cash reserve ratio (CRR) to control rate of inflation in the economy. Hence, the breakpoint of October 2011 in inflation rate series is a consequence of the upward review of CBN's Minimum Rediscount Rate (MRR) from 9.25 percent to 12 percent in October 2011. Furthermore, in 2015, the Central Bank of Nigeria reduced the Monetary Policy Rate (MPR) from 13 percent to 11 per cent culminating into the September 2015 breakpoint date in the interest rate series. Thirdly, in October 2015, JP Morgan expelled Nigeria from its Global Bond Index-Emerging Market (GBI-EM). GBI-EM is an index which tracks local currency bonds by emerging market governments. This decision led to the efflux of foreign investors holdings in Nigeria bonds. The effect was revealed in a breakpoint of December 2015 in the exchange rate series. Finally, there is a strong connection between economic growth and unemployment rate. According to the United Nations Development Programme 2016 annual report on Nigeria, the country's economy witnessed contraction (recession) for the first time in several decades. This resulted in an escalation of unemployment rate, especially amongst the youth, which led to the introduction of several government youth empowerment programmes to reverse the trend. The contraction was captured by the December 2016 breakpoint observed in the unemployment rate series. Thus, by introducing trend break functions in the unit-root tests without a priori information, we have been able to establish a good connection between the various breakpoints and the macroeconomic series. This is in line with previous works by Perron (1997), Zivot & Andrews (1992), Banerjee et al. (1992), Lumsdaine & Papell (1997), Ling et al. (2013), Arestis & Mariscal (2000), Basher & Westerlund (2008), Chiang & Ping (2008), Narayan & Smyth (2005), Ewing & Wunnava (2001) and many other studies.
III. CONCLUSION
By introducing trend break functions in the unit-root tests without a priori information, we have been able to establish a good connection between the various breakpoints and the macroeconomic series. These dates represent critical periods of policy changes by the government and external shocks. The unit-root tests with trend functions suggest that structural breaks in the macroeconomic variable series are very important and significant when formulating economic policies. The breakpoints can be included in a VAR model as deterministic terms to further improve the forecast/prediction power without affecting the asymptotic properties of the test statistics involved in the analysis.