
I. INTRODUCTION
The telecommunication and banking sector of Bangladesh have observed a tremendous growth in the last decade. The latest United Nations estimates says as of October 20, 2016 Bangladesh has a population of 163,483,818 (Worldometers.info, 2016). The total number of mobile phone subscriber in Bangladesh by December'19 is 165.572 million (Btrc.gov.bd, 2019). According to the Basic 2019 Statistics by ADB, people are mobile phone subscribers in Bangladesh (Asian Development Bank, 2019). Since the launch in 2011, the growth of Mobile Financial Services (MFS) has been very good. Especially in the past couple of years, growth numbers are sky-high. Compared to the data of November'14, the client number has increased by in November'15, which means an increase of 79 lakh clients in number. According to the latest data of Bangladesh Bank, on
November'19 the client of mobile banking was 3.47 crore. The growing trend of this sector can be further supported by the data comparing of last five years. A tremendous 554% growth can be noticed from 2013 to November'19. The client number was around 50 lakh in 2013 and by 2019 it became over 3 crore. 1311.21 corer transactions are happened on a daily basis through mobile banking (Bangladesh Bank, 2019). Till now, Bangladesh bank has given permission to 28 banks to run this MFS service but so far, 16 are in the business (Alo, 2019). Amongst all of them, 'bKash' is leading the market and Dutch Bangla bank's 'Rocket' is holding the second position. 'bKash' has 24 million subscriber with USD 7.5 million monthly (Asia Global Payment Summit, 2020).
According to another report published by USAID, despite of the high transaction cost, the growth has reached to $1.42 billion which is BDT 11,104 crore. Bangladeshi Mobile Financial Services users' altogether is accounted for 8% of the total registered users among the world (Mahbub, 2016). Given that, this service was launched in the country only five years ago this growth is amazing and also demands a study on why the subscribers are adopting the new service, what are the psychological reasons? Based on this information, it can be said that, banks have a very good opportunity of engaging root level people with basic banking activity, approved by Bangladesh bank (Bangladesh Bank, 2019) through mobile, which was not previously possible.
According to Godoe and Johansen's (2012) study, personality dimensions and system specific dimensions should be well studies before formulating and implementing any technological services. By understanding psychological issues of consumers in terms of adoption of mobile banking; mobile banking operators can decide what kind of electronic services can be provided to what type of customers, when and how- in order to increase market share and image (Musa S, 2014). Some key drivers have an impact for the adoption of mobile banking like- reduction of transaction cost, convenience, availability, timeliness, accessibility, usefulness and so on (Musa S, 2014). All these divers help to provide strategic benefits to the mobile banking operator company by providing better customers relationship management opportunities, increasing customers base and increasing market share and image (Musa S, 2014). But unfortunately much has not been done to understand the psychological reasons behind the adoption of this service in Bangladesh. As it is a growing market, the banks have launched those services on the basis of intuition, not in the basis of market investigation.
This paper therefore, argues for conducting a comprehensive study that will focus on the understanding determinates behind the adoption/use of mobile banking/MFS services in Bangladesh, for two reasons. Firstly, if determinates/what makes people use this service is not studied, then this booming industry might be in danger with the introduction of next new technology of transaction. Secondly, if the companies understand why their customers are adopting the service in-depth, then they will be able to reach more customers, grow their business and will be able to make more loyal customers.
II. LITERATURE REVIEW
a) Mobile Banking
In a broader sense, Mobile banking is a process of conducting financial transactions and banking activities through mobile phone or personal digital assistant. Mobile banking and making payments through mobile are two different concepts. Later only allows user to use mobile to pay electronically for the purchased goods and services either remotely or at point of sales (Rtn.bcc.net.bd, 2016). The exercise of different mobile devices to undertake financial businesses linked to client's bank account (Tran and Corner, 2016). With the help of three technological options Mobile banking is running like- SME – Based, mobile browser webs and mobile client applications.
b) Mobile Banking and Technology Acceptance Model (TAM) theory
Mobile banking has been developed 44 countries for unbanked but there is still shortage is research is noticed in terms of the adoption of mobile banking (Tobbin, 2012). To study the acceptance of a new technology like mobile banking, one of the best models available is the ‘Technology Acceptance Model’ (TAM). The theory was adopted from the Theory of Reasoned Action (TRA) (Fishbein and Ajzen, 1975) and was first proposed by Davis in 1986. This has been proven a great tool to explain and predict the behavior of the user regarding new technology (Legris, Ingham and Collerette, 2003). Park (2009), mentioned in his study that, TAM can explain why an user accepts or rejects a new technology, how the external variables influences some of the core attribute of human being such as belief, attitude and intention. Three key beliefs perceived ease of use (PEOU), perceived usefulness (PU) and attitude towards use (ATU) together can explain the user’s intention to actually use a new system (Davis et al., 1989). Davis (1993) defined PU as ‘the degree to which a person believes the system would enhance his performance and PEOU as ‘the degree to which using a particular system would ease his effort’. ATU is defined as ‘the degree to which individual evaluates and associates the target system with his or her job’. Though TAM has been used extensively to explain new technology adaption for many sectors but it is also argued that, the theory cannot fully explain the behavior as there are several other factors which influences the adaption which creates a need to extend the theory (Legris et al., 2003). For this reason, several new theories i.e. TAM 2 (Venkatesh and Davis, 2000), TAM 3 (Venkatesh and Bala, 2008), unified theory of acceptance and use of technology (Venkatesh et al., 2003) have been proposed. But still, a comparative study confirms the usefulness of TAM theory over other models (Mathieson, 1991).
TAM theory and several versions of it (i.e. TAM2, TAM 3) with other models have been used in different research perspectives in different context such as, e-shopping, e-banking, e-tourism, on-line tax filling etc. For example, in e-shopping in Pakistan; it was found that PEOU and perceived enjoyment are the most important factor. PU did not have that much impact in this case and is strongly dependent on PEOU. Similar study was done in Malaysia and there as well, PEOU was found to be the most important factor in case of adoption intention (Lim and Ting, 2012). Lu, Huang and Lo (2016) have applied TAM theory with variable integration from Theory of Planned Behavior (TPB) to understand the on-line tax filling appearance intention in Taiwan. Results show that PU and PEOU have a great impact. Along with these, 'tax equity', 'social norm' and 'moral norm' also have an important impact on adoption. In case of the adoption intention of e-learning study done in South Korea which integrates the constructs of TAM and e-learning self-efficacy, subjective norm, system accessibility, Park (2009) found that, e-learning self-efficacy was the most important construct. This discussion indicates two facts. The first one is, application of TAM theory in different geographic locations and for different industries showed different results which means if a specific industry's (in a specific country) adoption behavior is to be studied, then the theory has to be applied in that specific environment. The second fact is that, in most of the cases, scholars incorporated different theories with TAM to explain the adoption intention, which indicates that in some cases, TAM along may not be enough to explain adoption intention.
c) Mobile Banking Studies in Bangladesh
The research related to mobile banking services in Bangladesh has also received substantial academic attention. Literature explore different perspectives of mobile banking such as perception, customer satisfaction, loyalty, trust and so on For example, to understand the customer's perception service quality and its relationship with satisfaction and loyalty, a study was conducted by (Sagib and Zapan, 2014) with the use of SERVQUAL model and it was found that, three variables from the model – reliability and responsiveness, efficiency and convenience influences the satisfaction and only two of them reliability and efficiency influences the loyalty. A study by (Ahmed et al., 2011) says that the people who have adopted mobile banking in Bangladesh have done it because they think this is time saving, less costly and speedy. Their study also revealed that, highest number of people uses the service for ‘Air-time top-ups’. Another study done by (Islam, 2013) shows similar results. The study reveals that, in Bangladesh, users have adopted mobile banking because it is less costly, time saving, easy to access and trust worthy. However, those studies confirm to understand the post purchase behavior of mobile banking services. Very little research has been conducted so far to understand the pre purchase behavior such as customer intention, attitude, social influence, and its impact on the decision to use or not to use mobile banking services.
Furthermore, most of the studies are not theory-driven and no study has been conducted that applied TAM model. Only one study by Islam(2013)highlighted the trust issue but that was only for current users. The adoption intention and its relationship with trust for potential users have not been studied in Bangladesh. This validates this proposed study. Moreover, as the previous discussion indicates, cultural and geographical variables play an important role in determining the relationship; therefore, to understand the adoption intention well, a country-specific study is necessary.
d) TAM and Trust issue
Trust can be defined as a psychological expectation that a trusted party will not act opportunistically. Customer trust is known as a critical factor for the success of adoption of mobile banking. Many research papers have been found with the formation of mechanism of trust with the adoption of mobile banking. According to the study of (Siau and Shen, 2003), trust is classified into two categories- trust of technology and trust of mobile banking service providers and this is supported by Lee and Chung(2009), and in this study Lee and Chung(2009), focuses on three trust dimensions- trust in bank, trust in mobile network and trust in wireless infrastructure. In the context of mobile banking trusting intentions symbolizes consumers' willingness in terms of engagement in subsequent transactions with the service provider (Bhattacherjee, 2006). Higher level of trust in terms of service provider will lead to greater intentions of consumer's engagement in mobile banking transaction (Bhattacherjee, 2006).
TAM, along with its original model included different external variable to understand the intention and acceptance of particular behavior of interest. Perception, trust, social norm, economic factors are name of few. In case of many studies impact of different variable along with TAM is noticed. For example- In Ghana 85% people are not aware of mobile banking services. Most of the people in Ghana replied that they mainly want to use mobile banking services for time saving and convenience (Tobbin, 2012). There is some other motives like- availability, affordability, high interest of savings, trust, and security of resources. Along with easy to use and usefulness two other variables like-economic factors and perceived trust have an impact on mobile banking. Among variables, the use of trust factor with TAM for understanding technology adoption can be noted widely. For instance, to understand the first purchase intention of online shopping in Korea trust and TAM was integrated (Kim, 2012) and the result shows that trust in the form of company reputation, structural assurance, trusting stance and initial trust beliefs indirectly affects the intention and from the variables of TAM, only PU directly influenced the intention. The relationship of trust and TAM was explained in case of on-line shopping by (Gefen, Karahanna and Straub, 2003). According to their proposed model, in USA PEOU is an antecedent of trust, trust is an antecedent of PU and trust also directly influences the behavioral intention (BI). The result of this study is in line with the on-line tax adoption study in Taiwan, where researchers have also found necessity of trust factor. They proposed a model which incorporates the TAM, TPB and trust factor and they have given the opinion that in case of adopting a new technology like online tax, trust is equally important with PU and PEOU (Wu and Chen, 2005). This discussion indicates that, several scholars have considered trust as an important construct while studying adoption intention.
e) Integrating Trust and TAM in Case of Mobile Banking
Several study has also been conducted to understand the relationship between trust and the TAM theory in case of mobile baking (Pu “schel et al., 2010) have done a research in the developed cities of Brazil and proposed an integrated adoption intention framework specially for mobile banking where they proposed 13 independent variables (attitude, self-efficacy, compatibility, perceived behavioral control, results demonstrability, technology facilitation condition, resource facilitation condition, perceived ease of use, image, intention, subjective norm, testability, relative advantage and visibility) which explains the dependent variable (intention to adopt mobile banking) by 69% in case of non-users.
Tobbin(2012), finds in his study done on the rural dwellers of Ghana that PU and PEOU along with the economic factor and trust have a great impact on the rural people in adopting mobile banking service.
A study done on New Zeland's young adults by Tran and Corner (2016), indicates that most important factors in creating usage intention for mobile banking is PU followed by perceived credibility and perceived costs. Besides that, one of the most persuasive ways of building trust according to them is face-to-face communication.
A study done in UK by Lewis, Palmer and Moll (2010), indicates that in case of young consumers, compatibility, perceived usefulness and risk are significant indicators in case of the adoption of mobile banking. Not only compatibility had direct effect but also it was identified as very important antecedent for PEOU, PU and also credibility. They have also indicated that, trust and credibility are very crucial in case of reducing the perceived risk. One very important implication of this study is the exceptionally high variance (65%; typical rate 40%) in intention to adopt the system seeks the attention of the scholars to further reconfirming of the model.
In a cross cultural study done by Mortimer et al.(2015), it was found that in case of the adoption intention of Australian consumers, most important variables are, PU, PEOU and perceived risk (PR) and in case of Thailand, the variables are PU, PR and social influence.
While examining the role of PU, PEOU, PR and self-efficacy for mobile banking in Jordan, Alalwanet al.(2016), found that the adoption intention is significantly influenced by PU, PEOU and PR.
A study in Trukey reveals that, in case of the young users, along with perceived usefulness, perceived social risk & perceived performance risk are also important (Akturan and Tezcan, 2012).
While the adoption intention was studied with the variables perceived risk, brand awareness, and brand image of MBS providers in Taiwan, it was found that even in a single country, perceived risk and innovation benefits have different impact on the users with different behavioral pattern. Brand awareness and brand image of the service provider also had a mentionable impact (Chen, 2013).
Another study by Luarn and Lin's (2005), says risk have a superior impact than PU in case of adoption intention in Taiwan.
Laforet and Li(2005), have found out that, the mobile banking users in China are predominantly male and the main barrier in adopting the system is the lack of awareness, lack of understanding of the benefit provided by the system, concerns about hacking and fraud which.
In order to understand the adoption intention of the customers of India, a study was done by Deb and David (2014). They incorporated factors from TAM, diffusion of innovation model (DOI) - influence of society (SI), facilitating condition, PEOU & PU) along with the trust facts (perceived competence, perceived benevolence, perceived privacy & security and communication) important for the technology adoption. From the study they found that, two of the trust factors among four – benevolence and privacy & security have negative impact on the adoption, which means these factors can create hindrance to the adoption. Another variable having negative relationship with adoption was facilitating condition which was explained by the economic factors by the researchers.
Similar study done by Chauhan (2015), in India depicts slightly different result. In this case the study finds an impact of trust and PU has an impact but it didn't find any impact of PEOU in case of adoption.
One of the major criticisms of the TAM theory is it was tested for the work-related issues which did not involve any monetary issue where the user actually has to get involved in monetary transaction. The original model was tested in case of the adoption of the personal computer where personal transaction or monetary fact is not related. It is very obvious that, wherever monetary fact is involved, trust becomes a major issue (Chircu and Kauffman, 2000).
All these researches indicate that trust is a very crucial part of the adoption model for almost all the countries. Moreover, inconsistent results can be seen for different countries. This difference highlights the fact that, adoption intention variables are different in different cultures and unless a study on Bangladeshi people on adoption intention of mobile banking is not done, getting a clear understanding is not possible.
f) Complexity in Mobile Banking
Complexity is the degree of innovation which is relatively considered as difficult to understand and use. It's a direct effect on consumer's adoption of mobile banking service (khraim, Shoubaki, & Khraim, 20 november, 2011). Related researcher found that it negatively influences the adoption of internet users or consumers. It is the reverse of ease of use and it's a major factor in mobile banking adoption. Mobile technology suggests that intension of mobile banking is inhibited by the perceived complexity of the innovation. Users will be inhibited to use of mobile banking if it finds more mental effort, time consuming or frustrating. There are some barriers in a number of studies which are complexity in use, technical infrastructure and design of technology. Therefore, it is hypothesized that perceived complexity inhibits mobile banking adoption (Al-Jabri & Sohali, 2012).
Complexity registries collected frequency of responses relatively two variable which are one variable is “using complicated” and another is requires “knowledge and learning”(Cruz & laukkanen, nov 5, 2010). There is significant research on the mobile banking which recommend that mobile banking s the hindered by complexity of the innovation. This means that barriers of mobile banking are largely related to the technology infrastructure and design.
g) Relationship between compatibility and mobile banking
Compatibility can be extended with a new service that consist of users, existing values, beliefs, previous experience, habit that faster increase of innovation. Its conforming individuals' user's lifestyle for faster adoption (Lewis, Palmer, & Moll, 2010). Compatibility now integrated with TAM model in the virtual store's context. It will lead to higher perceived ease of use that's effort is required. The innovative are likely get trust underlying the technology through more competence.(Al-Jabri & Sohali, 2012) This presence beliefs of compatibility are very useful for explaining mobile banking adoption. it will lead to higher behavior intension use of mobile banking.
Compatibility is assumed to be consistent with socio-culture values, belief as well as need of potential adopters. Its sincere conformance can significantly increase mobile banking adoption rate. Between an innovation and existing product incompatibility services may inhibit an adopter's acceptance. Many researchers (Chen, 2013) demonstrated that it is significant which is determining consumer's attitude toward virtual store. It affects consumer willingness to adopt an innovation to mobile banking. Numerous recent studies have also provided supporting evidence to the adoption of mobile banking through compatibility. The degree which innovation is considered with existing value of users.
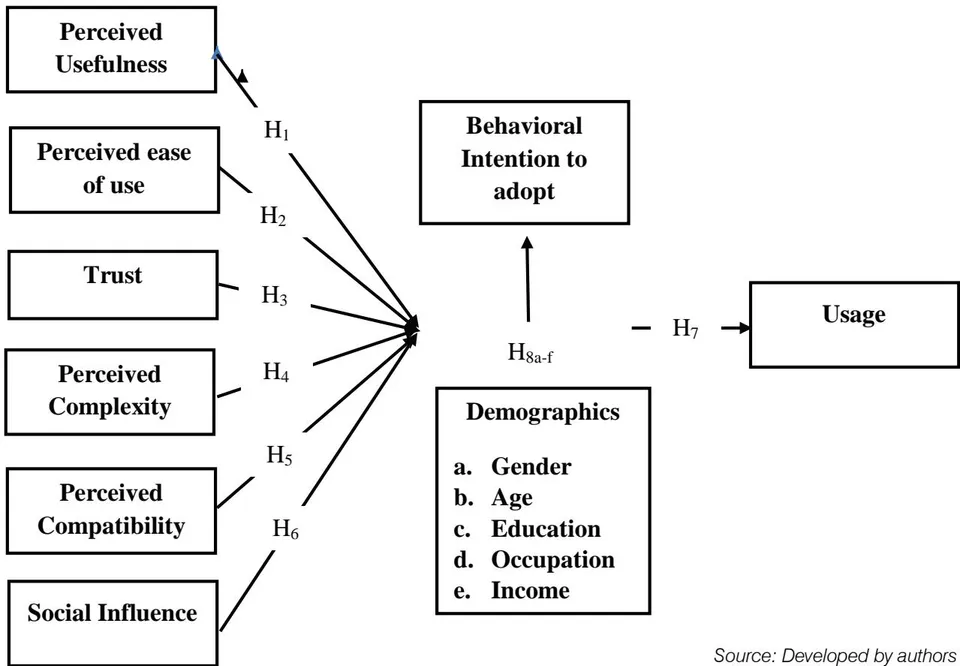
i) Conceptual Framework
h) Social influence on Behavioral Intention
(Riquelme & Rios, january 2010)Social norms are that factors which are related to family, friends, and relative. It's a relevant concept to explain the adoption of technology or mobile banking. It cannot be ignored because of their adoption and behavior contribution. Social influences significantly affect an individual's intention to use the mobile banking. Some researcher discovers that individual's decision to adopt mobile banking services are influenced by social network like family, friends or others. As for the mobile banking, social environment is influenced by a customer intention to mobile banking adoption. (Alalwan, dwivedi, & Rana, 2017)Information and encouragement play a dynamic role in contributing customer awareness by surrounding people. Social influence is a person's perception that are performed by individual. In the context,(Gu, Lee, & Suh, 2009) mobile banking will be useful when customer get recommendation from colleague, friend or family member. It positively affects behavioral intention of customer in mobile banking.
III. METHODOLOGY
In this paper, the quantitative method has been used. Both primary and secondary data has been collected. For the collection of primary data, the researchers have chosen convenient sampling technique; 339 respondents have been chosen throughout the country who are using mobile banking services. Among 339 data, 300 has been used for this paper. On the other hand, for the collection of
Regression Equation 1
secondary data, different kinds of journals, papers, blogs, websites, articles, newspapers, and magazines have been used. The data is analyzed through SPSS and Microsoft software. The paper is conclusive in nature and both metric (nominal and ordinal level data) and non-metric (Interval and ratio data) are used for the analysis of this paper. The equation of statistical model which have been analyzed from the survey data is shown below:
Here,
Y = Behavioral intension to adopt
faster banking transaction, easier transaction, beneficial, control over finance, more convenient, easy to use, easy learning, become skillful, clear and understandable, easily works, trustworthy, potential risk, confidentiality, safe uses on smartphone, require of mental effort, frustrating, requires knowledge and learning, comparable with life style, managing finance, keep fit with working style, think important, most people use, becoming familiar, intercept of the line, e= error associated with the model.
Regression Equation 2
Here,
Y = Usage
use of mobile banking is worthy, intercept of the line, e= error associated with the model.
IV. DATA ANALYSIS AND PRESENTATION
The author collected data from survey questionnaire and analyses this through SPSS software. Moreover, in this paper 300 data are collected from customer who are involved with mobile banking.
a) Demographic Information
Gender: All respondents are not only male or female. In this demographic profile there are 15.33% are female respondents and 84.67% are male respondents and total respondents are 300. So, here male respondents are more than female.
Age: In this demographic profile, 63.67% are respondent's age are belonging to below 24. 28.67% respondent's ages are belonging to 25-40 and 1% respondent's ages are belongs to above 40. Where total respondents are 300.
Educational Background: From 300 respondents, respondent's educational background is graduation. respondent's educational background is college level and others respondent's .
Occupation: From 300 respondents, 15.67% respondents are businessman, 18.33% respondents are private service holder, 51.33% are others and 7.00% are govt. service holder.
Income: In this demographic profile, 55.33% are respondent's income is less than BDT 10,000. 16.67% respondent's income is less than BDT 20,000 and 23.67% respondent's income is less than BDT 50,000. Where total respondents are 300.
Mobile banking services company: From 300 respondents, 61.33% respondents use Brac Bank (bkash), 31.00% respondents use DBBL Mobile Bank (rocket) and 0.67% respondents use others like mercantile bank and UCash.
b) Hypotheses Testing
Hypotheses 1
Null Hypotheses: perceived usefulness has not positive effect on behavioral intention. Alternative Hypotheses: perceived usefulness has positive effect on behavioral intention.
Model Summery
| Model | R | R Square | Adjusted R Square | Strength of Association | Sid. Error |
| Usefulness and Behavioral intention to adopt to adopt | .087 | .071 | Very strong | .76288 |
From the table it has shown that Pearson Correlation (r) is.29 and the value of R square is.87 which expresses that there is a positive relation between perceived usefulness and behavioral intention. Adjusted R square value is.71 which implies that independent variables are perfect and dependent variable can be changed. For this model summary the regression equation is
ANOVA Testing
| ANOVA Table | ||||||
| Model | Sum of Squares | Df | Mean Square | F | Sig | |
| 1 | Regression | 16.265 | 5 | 3.253 | 5.590 | |
| Residual | 171.105 | 294 | .582 | |||
| Total | 187.370 | 299 | ||||
Predictors: (Constant), Mobile banking is more convenient, Mobile banking is beneficial, using mobile banking enables me to do my banking transactions faster, Mobile banking gives me greater control over my finances than traditional forms of banking, using mobile banking makes it easier to perform my banking transactions.
From the ANOVA table, the researcher get F value is 5.590 which significant level is 0.05 and calculated critical F value is 2.245 therefore, F distribution is larger than calculated critical value (5.590>2.245) it means that the null hypothesis is rejected.
Hypotheses 2
Null Hypotheses: perceived ease of use has not positive effect on behavioral intention. Alternative Hypotheses: perceived ease of use has positive effect on behavioral intention.
Model Summery
| Model | R | R Square | Adjusted R Square | Strength of Association | Sid. Error |
| Ease of use and Behavioral intention to adopt | .090 | .075 | Very strong | .76151 |
From the table it has shown that Pearson Correlation (r) is.30 and the value of R square is.90 which expresses that there is a positive relation between perceived ease of use and behavioral intention. Adjusted R square value is.75 which implies that independent variables are perfect and dependent variable can be changed. For this model summary the regression equation is
ANOVA Testing
| ANOVA Table | ||||||
| Model | Sum of Squares | Df | Mean Square | F | Sig | |
| 1 | Regression | 16.878 | 5 | 3.376 | 5.821 | |
| Residual | 170.492 | 294 | .580 | |||
| Total | 187.370 | 299 | ||||
Dependent Variable: To use mobile banking is worthy
Predictors: (Constant), I easily understand how mobile banking works, Mobile banking is easy to use, it is easy to become skillful in mobile banking, Mobile banking is clear and understandable, learning to use mobile banking is easy.
From the ANOVA table, the researcher get F value is 5.821 which significant level is 0.05 and calculated critical F value is 2.245 therefore, F distribution is larger than calculated critical value (5.821>2.245) it means that the null hypothesis is rejected.
Hypotheses 3
Null Hypotheses: Trust has not positive effect on behavioral intention.
Alternative Hypotheses: Trust has positive effect on behavioral intention.
Model Summery
| Model | R | R Square | Adjusted R Square | Strength of Association | Sid. Error |
| Trust and Behavioral intention to adopt | .073 | .060 | Very strong | .76740 |
From the table it has shown that Pearson Correlation (r) is.27 and the value of R square is.73 which expresses that there is a positive relation between trustworthiness and behavioral intention. Adjusted R square value is.60 which implies that independent variables are perfect and dependent variable can be changed. For this model summary the regression equation is
ANOVA Testing
| ANOVA Table | ||||||
| Model | Sum of Squares | Df | Mean Square | F | Sig | |
| 1 | Regression | 16.878 | 5 | 3.376 | 5.821 | |
| Residual | 170.492 | 294 | .580 | |||
| Total | 187.370 | 299 | ||||
Dependent Variable: To use mobile banking is worthy
Predictors: (Constant), My banking on a smart phone is safer than using laptop or desktop, I think mobile banking has a potential risk, I think mobile banking is trustworthy, I think mobile banking puts personal details at risk for confidentiality
Hypotheses 4
From the ANOVA table, the researcher get F value is 5.792 which significant level is 0.05 and calculated critical F value is 2.402 therefore, F distribution is larger than calculated critical value (5.792>2.402) it means that the null hypotheses are rejected.
Null Hypotheses: Perceived complexity has not positive effect on behavioral intention.
Alternative Hypotheses: Perceived complexity has positive effect on behavioral intention.
Model Summery
| Model | R | R Square | Adjusted R Square | Strength of Association | Sid. Error |
| Complexity and Behavioral intention to adopt | .068 | .058 | Very strong | .76819 |
From the table it has shown that Pearson Correlation (r) is.26 and the value of R square is.68 which expresses that there is a positive relation between perceived complexity and behavioral intention. Adjusted
R square value is.58 which implies that independent variables are perfect and dependent variable can be changed. For this model summary the regression equation is
ANOVA Testing
| ANOVA Table | ||||||
| Model | Sum of Squares | Df | Mean Square | F | Sig | |
| 1 | Regression | 12.697 | 3 | 4.232 | 7.172 | |
| Residual | 174.673 | 296 | .590 | |||
| Total | 187.370 | 299 | ||||
Dependent Variable: To use mobile banking is worthy
Predictors: (Constant), Using mobile banking requires knowledge and learning, using mobile banking requires a lot of mental effort, using mobile banking can be frustrating
From the ANOVA table, the researcher get F value is 7.172 which significant level is 0.05 and calculated critical F value is 2.635 therefore, F distribution is larger than calculated critical value (7.172>2.635) it means that the null hypotheses are rejected.
Hypotheses 5
Null Hypotheses: Perceived compatibility has not positive effect on behavioral intention.
Alternative Hypotheses: Perceived compatibility has positive effect on behavioral intention.
Model Summery
| Model | R | R Square | Adjusted R Square | Strength of Association | Sid. Error |
| Compatibility and Behavioral intention to adopt | .060 | .050 | Strong | .77153 |
From the table it has shown that Pearson Correlation (r) is.24 and the value of R square is.60 which expresses that there is a positive relation between perceived compatibility and behavioral intention.
Adjusted R square value is.50 which implies that independent variables are perfect and dependent variable can be changed. For this model summary the regression equation is
| ANOVA Table | ||||||
| Model | Sum of Squares | Df | Mean Square | F | Sig | |
| 1 | Regression | 11.173 | 3 | 3.724 | 6.257 | |
| Residual | 176.197 | 296 | .595 | |||
| Total | 187.370 | 299 | ||||
Predictors: (Constant), People who are familiar with me think that I should use mobile banking, People who are important to me think that I should use mobile banking, most people around me use mobile banking.
From the ANOVA table, the researcher get F value is 6.257 which significant level is 0.05 and calculated critical F value is 2.635 therefore, F distribution is larger than calculated critical value (6.257>2.635) it means that the null hypotheses are rejected.
Hypotheses 6
Null Hypotheses: Social influence has not positive effect on behavioral intention.
Alternative Hypotheses: Social influence has positive effect on behavioral intention.
Model Summery
| Model | R | R Square | Adjusted R Square | Strength of Association | Sid. Error |
| Social influence and Behavioral intention to adopt | .064 | .054 | Very strong | .76983 |
From the table it has shown that Pearson Correlation (r) is.25 and the value of R square is.64 which expresses that there is a positive relation between social influence and behavioral intention. Adjusted R square value is.54 which implies that independent variables are perfect and dependent variable can be changed. For this model summary the regression equation is
| ANOVA Table | ||||||
| Model | Sum of Squares | Df | Mean Square | F | Sig | |
| 1 | Regression | 11.173 | 3 | 3.724 | 6.257 | |
| Residual | 176.197 | 296 | .595 | |||
| Total | 187.370 | 299 | ||||
Dependent Variable: To use mobile banking is worthy.
Predictors: (Constant), People who are familiar with me think that I should use mobile banking, People who are important to me think that I should use mobile banking, most people around me use mobile banking.
From the ANOVA table, the researcher get F value is 6.729 which significant level is 0.05 and calculated critical F value is 2.635 therefore, F distribution is larger than calculated critical value (6.729>2.635) it means that the null hypotheses are rejected.
Hypotheses 7
Null Hypotheses: Behavioral intention has not positive effect on mobile banking usage.
Alternative Hypotheses: Behavioral intention has positive effect on mobile banking usage.
Model Summery
| Model | R | R Square | Adjusted R Square | Strength of Association | Sid. Error |
| Behavioral intention to adopt and usage | .086 | .083 | Very strong | .70359 |
From the table it has shown that Pearson Correlation (r) is.29 and the value of R square is.86 which expresses that there is a positive relation between behavioral intention and usage. Adjusted R square value is.83 which implies that independent variables are perfect and dependent variable can be changed. For this model summary the regression equation is
ANOVA Testing
| ANOVA Table | ||||||
| Model | Sum of Squares | Df | Mean Square | F | Sig | |
| 1 | Regression | 13.876 | 1 | 13.876 | 28.031 | |
| Residual | 147.520 | 298 | .495 | |||
| Total | 161.397 | 299 | ||||
| Dependent Variable: I will use mobile banking in the futurePredictors: (Constant), To use mobile banking is worthy |
From the ANOVA table, the researcher get F value is 28.031 which significant level is 0.05 and calculated critical F value is 3.872 therefore, F distribution is larger than calculated critical value it means that the null hypotheses are rejected.
Regression and Correlation analysis
| Model | R | R Square | Adjusted R Square | Strength of Association | Sid. Error |
| Usefulness and Behavioral intention to adopt | .087 | .071 | Very strong | .76288 | |
| Ease of use and Behavioral intention to adopt | .090 | .075 | Very strong | .76151 | |
| Trust and Behavioral intention to adopt | .073 | .060 | Very strong | .76740 | |
| Complexity and Behavioral intention to adopt | .068 | .058 | Very strong | .76819 | |
| Compatibility and Behavioral intention to adopt | .060 | .050 | Very strong | .77153 | |
| Social influence and Behavioral intention to adopt | .064 | .054 | Very strong | .76983 | |
| Behavioral intention to adopt and usage | .086 | .083 | Very strong | .70359 |
| Hypotheses Testing | ||||||
| Hypotheses | B | T statistic | Critical value | sig | Result | remark |
| H1 | 5.383 | 7.773 | 1.976 | .000 | 7.773>1.976 | Rejected |
| H2 | 4.999 | 6.885 | 1.976 | .000 | 6.885>1.976 | Rejected |
| H3 | 4.317 | 6.642 | 1.976 | .000 | 6.642>1.976 | Rejected |
| H4 | 4.834 | 9.546 | 1.976 | .000 | 9.546>1.976 | Rejected |
| H5 | 4.680 | 9.220 | 1.976 | .000 | 9.220>1.976 | Rejected |
| H6 | 4.700 | 7.379 | 1.976 | .000 | 7.379>1.976 | Rejected |
| H7 | 4.610 | 15.831 | 1.976 | .000 | 15.831>1.976 | Rejected |
| ∞=0.05, df= | ||||||
V. LIMITATIONS AND FURTHER STUDY
The major limitations for this paper includes – respondents, resources, knowledge and, budget. Firstly, as respondents were not always available and sometimes were not willing to give time, degree of difficulties were faced. Moreover, for finding suitable respondents for this paper, researchers also faced challenges. Secondly, resources are limited to conduct the paper. Thirdly, it is difficult to identify determinates regarding consumers intention to use mobile banking, limitation of appropriate knowledge in this arena would consider as another problem. Finally, budget is considered as another limitations. For the completion of paper, researchers had to reach 339 respondents, more respondents would be covered if more budget can be raised. The researchers will work with further factors of affecting consumer's intention towards using mobile banking. By conducting, factor analysis, it would be understood which factors are most significant in terms of using mobile banking.
VI. MAJOR FINDINGS, CONCLUSION AND RECOMMENDATIONS
In this paper it is find out that, people basically adopt mobile banking for its easiness as highest significant value is noticed here (.90). Another important factor is identified which is social influence. From the table it is seen that, social factors has one of the most significant values which is (.64). People install bKash app during festivals in order to get discounts or instant cash back offer. Via social media various companies, now offering discounts through bKash payment, so it is considered as one of the important factor in order to understand customer's pre-purchase conception. Though trust has.73 significant value, most of the respondents faced security related problems like- many unwanted and fraud call were received by asking bKash and rocket password in order to get bonus. People who are living in rural areas mostly lost money due to fraudulent. Due to various fraudulent cases, mobile banking companies started campaign by telling not to share password with anyone by in rural areas people are still facing this kind of issues. People find to use mobile banking is very useful, and less complex. With the help of mobile banking services people can also recharge mobile anytime at anyplace so it saves time and, cost.