I. INTRODUCTION
The issue of inflation volatility is a recurrence decimal in the challenges confronting developing countries (Danmola, 2013), creating serious concern among stakeholders (the government, monetary authority, various sectors of the economy and the people) in the economy. This is due to its adverse effects on the economy, which have been widely documented in countries of diverse economic structures and monetary policy frameworks (Omotosho and Doguwa, 2011). These include higher risk premium, hedging costs, and unforeseen redistribution of wealth, economic instability and reduction in overall economic growth. Countries with high inflation have significantly higher levels of volatility, which invariably impacts on sectoral or aggregate growth negatively.
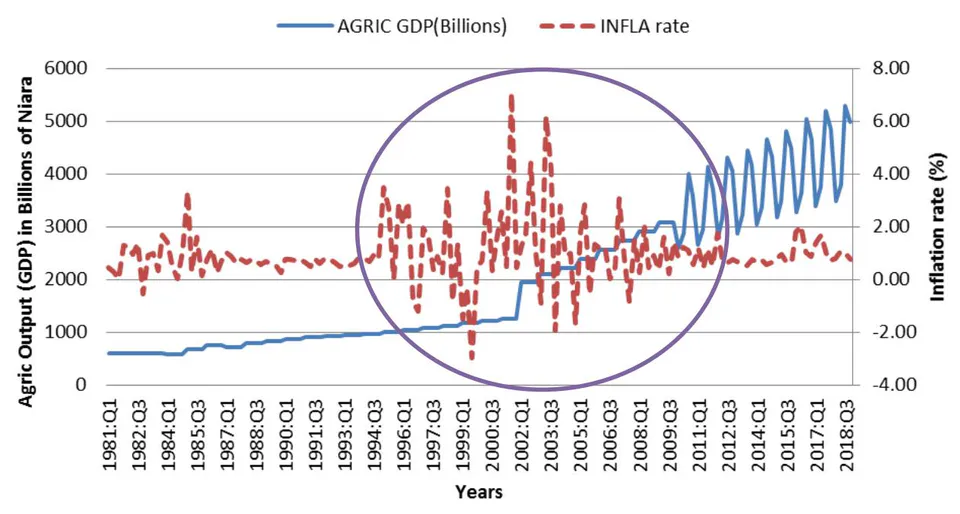
Figure 1 below shows the trend of both inflation rate and agricultural output from 1981:1 to 2018:4. There is consistency in the direction of both variables, showing fluctuations all through the period of consideration, especially the inflation rate. The persistent fluctuation of the inflation rate calls for concern as per what its effect (coupled with other macroeconomic indicators) will be on a real sector like agriculture. The importance and place of agriculture in Nigeria economy growth and development make it a worthwhile effort to examine the effects of macroeconomic indicators dynamic on agricultural output. Over the time as inflation rate increased, agricultural output also increased, although agricultural output fluctuated during the upward movement over the period.
The investigation into inflation volatility and it impact has involved a number of methods in which Generalised Autoregressive Conditional Heteroscedasticity (GARCH) is one. For example, country's headline Consumer Price Index (CPI) series conditional variance was estimated with its attendance impacts on other macro-economic variables (Idowu and Hassan, 2010; Udoh and Egwaikhide, 2008; and Adamgbe, 2004). Rother (2004) considered discretionary fiscal policies and inflation volatility and suggests that discretionary fiscal policies has contributed to inflation volatility in a range of Organisation for Economic Co-operation and Development (OECD) countries between 1967 and 2001. Fielding (2008) used monthly time-series data on the prices of 96 individual products in the 37 states of Nigeria to analyse the factors that drive inflation volatility. Average inflation rates, transport and communication infrastructure, consumer access to credit markets and urbanization were found to be significant determinants of volatility.
However, previous studies in Nigeria have failed to evaluate the impact of inflation volatility on individual sectors of the economy like agricultural sector, industrial sector, etc. Given the incessant crisis in the petroleum sector, fluctuation in the barrel price of oil, the experienced recession in the economy, the agricultural sector has found considerable attention to boost the Nigerian economy. The question then is: To what extent are volatilities of selected macroeconomic indicators impacting on agricultural growth in Nigeria? The study estimated this impact for Nigeria by using quarterly data for the period 1981 to 2018.
II. THEORETICAL FRAMEWORK
The cost-push theory of inflation was considered to analyse the impact of inflation volatility on agricultural growth in Nigeria. According to Kalkuhl et al (2013), the production of agricultural commodities is dependent on external circumstances. These external circumstances cause the cost of agricultural produce to rise.
Increase in aggregate demand generally results in price rise. However, when there is increase in costs (independent of any increase in aggregate demand), prices may still rise. According to Ahuja (2012), increase in prices of raw materials (especially energy inputs such as rise in crude oil prices) as well as rise in wage rate of labour can bring about cost-push inflation. Danmola (2013) argued that inflation-created problems in Nigeria led the government to devalue the currency (naira). This in turn causes the price of imported goods to rise, leading to increase in cost of production (since Nigeria imports a lot of raw materials needed for production).
III. MODEL SPECIFICATION
a) Determination of Inflation Volatility
To determine the level of inflation volatility in Nigeria, this study generated the volatility of inflation by employing the Generalised Autoregressive Conditional Heteroscedasticity (GARCH) techniques. Engle (2001) used an autoregressive time series approach to account for persistence in volatility estimation. He assumes that the volatilities are conditional on each other over time. Engle's model, which is sometimes referred to as the Normal ARCH model, is defined as:
where both the intercept and the parameter coefficient are non-negative so that the volatility estimation is positive. The returns are also assumed to be normally distributed with a mean of zero and variance of , conditional on all information up to the current time.
Today's volatility may not depend only on yesterday's returns hence many lags of returns can be included in the model. This is called the ARCH (q) model:
The avoidance of the large values of q in Engle's ARCH model by Bollerslev (1986) resulted in the generalized autoregressive conditional heteroscedasticity (GARCH) model. The GARCH model allows for a longer memory process with more flexibility. The GARCH model assumes normality, and includes previous estimates of volatility in the calculation:
the GARCH model can be extended to the GARCH (q, p) model (like in the case of ARCH model extended to the ARCH (q) model). This follows that:
where the intercept and the coefficients must be non-negative to ensure that the volatility estimate is positive.
The GARCH model above is typically called the GARCH model. The in parentheses is a standard notation in which the first number refers to how many autoregressive lags, or ARCH terms, appear in the equation, while the second number refers to how much moving average lags are specified, which here is often called the number of GARCH terms. simply implies to the first order autoregression.
Rule of Thumb
If , there is no volatility,
, there is volatility, and
, there is overshooting (i.e. excessively volatile) Where and represent ARCH and GARCH respectively.
b) Macroeconomic Indicators and Agriculture Output
Having established the volatile nature of selected macroeconomic indicators considered by the study. The paper employed the fully modified ordinary least square (FMOLS) estimation method to empirically analyse the effect of the dynamics of these macroeconomic indicators on agricultural output. The responsiveness of agricultural output to macroeconomic volatility was established.
The model follows:
Where;
represents agricultural output
represents inflation volatility
The paper concentrated on inflation rate and exchange rate volatility due to two main reasons: first, the general price movement gives the value for most agricultural output and also regulates the demand for and supply of agricultural produces in the market. Second, the currency rate determines the inclusion of foreign investment and further regulates the foreign market or trade of agricultural products. Therefore, the paper extended equation (5) to include a representative of cost of fund i.e. the interest rate, which is seen to determine the access to funding and borrowing by the agricultural sector agents (farmers and agripreneurs), respectively. Hence, equation (6).
The above model is expressed explicitly in log-linear form as:
Where;
represents natural logarithm of agricultural output
represents inflation volatility
represents natural logarithm of money supply
represents exchange rate
represents interest rate
represents summation n represents the quarter 2018:4
i represents the quarters 1981:1, 1981:2, 1981:3,... n
represents the error term
The a priori expectation of all the variables (inflation volatility inclusive) are expected to have missed impact on agricultural output. Thus, the parameters of estimation are expected to be:
IV. DATA DESCRIPTION
The study make used of quarterly time-series data from various published Central Bank of Nigeria (CBN) statistical bulletin from 1981 to 2018 to analyze the impact of inflation volatility on agricultural growth in Nigeria. The model specification consists of agricultural output (AGR) measured in billion naira, inflation rate (IFR) which is in percentage change, exchange rate (EXR) is the value of naira to one US dollar, interest rate (INR) is in percentage. Agricultural output is made-up of crop production, livestock, forestry and fishing. Thus, agricultural output is measured by the production made in these four sections. Inflation volatility (IFV) is measured by the fluctuations or instability in the rate of inflation using the GARCH technique. The residual of the GARCH estimates is extracted and the series was used as a measure of the inflation volatility.
Exchange rate is the price of the Nigerian naira for another country's currency. Interest rate is simply a rate paid for the use of money. A decrease in interest rate will lead to an increase in inflation (i.e. demand-pull inflation) as the demand for money will rise. Table 1 shows the summary of the data for all variables in the model. This shows the spread of the data employed in the study.
| Statistics | Agric. GDP (AGR) | Exchange Rate (EXR) | Interest Rate (INR) | Inflation Rate (IFR) |
| Mean | 1923.38 | 109.09 | 17.84 | 0.97 |
| Median | 1193.08 | 106.07 | 17.58 | 0.76 |
| Std. Deviation | 1318.08 | 102.64 | 5.03 | 1.22 |
| Variance | 10530 | 25.33 | 1.48 | |
| Skewness | 0.843 | 1.26 | 0.48 | 1.43 |
| Kurtosis | -0.461 | 1.73 | 1.75 | 6.67 |
| Range | 4712.50 | 454.69 | 29 | 10.06 |
| Minimum | 575.88 | 0.57 | 9 | -2.98 |
| Maximum | 5288.30 | 455.26 | 38 | 7.08 |
| Number of observations | 152 | 152 | 152 | 152 |
V. MODEL ESTIMATION
The empirical estimations and interpretation were reported in this section. This is divided into two main thrust: first, the paper establish the level of volatility present in the selected macroeconomic indicators and second, determine the effect of these macroeconomic indicators (exchange rate, inflation rate, and interest rate) on agricultural outputs in Nigeria.
a) The Volatility Level in
The paper examined the volatile attributes of selected macroeconomic indicators selected (i.e. inflation and exchange rate). The results were depicted in Table 2. It shows that using the GARCH methodology,
Source: Authors' Computation (2019) inflation rate and exchange rate are significantly volatile. The GARCH coefficients show that the inflation volatility is not explosive however, the pressure of reaching an explosive area is observed from the growth of general prices. The exchange rate was also volatile and it indicates the high risk associated to exchange rate driving investments.
| Inflation Rate | Exchange Rate | |||
| Coefficient | Prob. | Coefficient | Prob. | |
| Mean Equation: | ||||
| Lagged Value of Inflation | 0.7712 | 0 | ||
| Lagged Value of Exchange rate | 0.6783 | 0 | ||
| Variance Equation | ||||
| ARCH (1) | 0.3016 | 0.0127 | 0.1809 | 0.0005 |
| GARCH (1) | 0.6945 | 0 | 0.3845 | 0.0023 |
| Constant | 0.0722 | 0.0005 | 0.0402 | 0 |
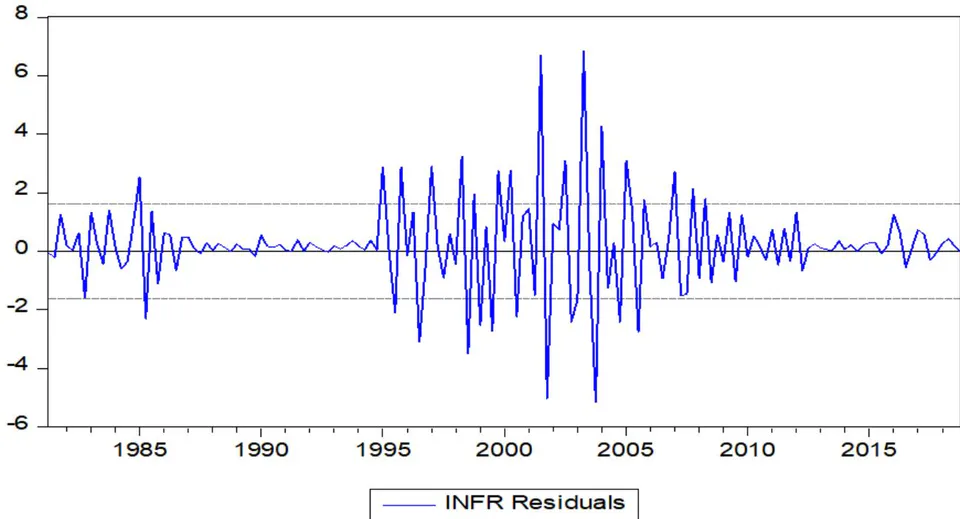
Based on the summation of the coefficients of ARCH and GARCH estimators, it is evident that inflation and exchange rates in Nigeria for the period 1981:1 to 2018:4 are volatile and the convergence might not be recommended soon (i.e. tends towards 1:0.3016 + 0.6945 = 0.9961). Figure 2 established the volatile nature of the residuals of inflation rate. This implies that inflation rate volatility began rising momentum in 1995 when the old price regulation was abolished due to change in government. Between 2000 and 2005 the volatile nature of inflation rate increased tremendously with rising pressure until 2008. This is evident on the trend significantly falling outside the empirical threshold given by default.
b) Determining the Effects of Macroeconomic Indicators Dynamics on Agricultural Output
Table 3 consists of models I–IV were estimates of the effect of the dynamics of macroeconomic indicators on agricultural output. Inflation rate volatility has substantial adverse effect on agricultural output in all the models estimated. This effect was majorly pronounced in model III which is the model of concern in the paper. This suggests that the frequent changes in the general price of agricultural produces discourage production in the agricultural sector. The findings corroborate the submission of Kalkuhl et al. (2013), which confirm that the effect of price volatility cannot be undermined in making decision that will propel output growth in the agricultural sector. Compared to model 1, the impact was slightly lower, which shows that with the absence of cost of fund, the effect of inflation volatility will be significantly felt in the agricultural sector. It is apparent that, the absence of the interest rate activities in the model had remove the possibility of the expansionary effect of optimal cost of fund – easy access to finance by the agents of agricultural sector.
The implication of the effect of inflation volatility on agricultural output is central on the attitude and prospective investment returns of agricultural sector investors. First, in terms of attitude, the harmful effect of inflation volatility will make the downward price trajectories of the agricultural produces unpredictable and thus, increases the magnitude of expected losses observed in investment. Second, the gradual decrease in the prospective investment returns could discourage the volume of investment channel to agricultural sector in the short and medium terms, respectively. The effect of interest rate in model III (model of reference) has adverse effect on agricultural output in Nigeria. This is evident when compared with what was experienced in other models, as the effect seems to be consistent. The response from interest rate is supported by the findings of Fielding (2008) and Idowu and Hassan (2010). These studies found that the cost of funds had adverse effect on agricultural output. In the work of Idowu and Hassan (2010), the inclusion of interest rate was justified to control for the disparity in access to fund by the agricultural sector as against other sectors of the economy. While the work of Omotosho and Dougwa (2011) found contradictory result, the reason proffered was that the number of observation considered covered by the study was characterized by the crises.
The exchange rate has positive effect on agricultural output. The depreciation of the naira against the universal unit of measurement has significant effect on the cost of production and the tradability of agricultural produces. This effect can be explained on the ground that rising exchange rate (decline in naira value) has increasing effect on cost of production as the economy is highly import dependent. More so, it also has an indirect effect on tradability of agricultural products. This tradability effects occur has a result of exports dynamics and cyclical trade deficit of agricultural produces.
The results indicate that rising inflation rate increases agricultural output under the period considered in the study. This implies that the concurrent increases in both the general price level and the prices of agricultural produces stimulate agricultural output and therefore, necessitates the moderate increase in prices of agricultural produce to encourage investment in the Nigeria's agricultural sector. This effect was robust to changes in the specification of the model. Hence, positive effect of inflation rate on agricultural output remains dominant across the alternative specification of the models. All the results possess varying degree of explanatory prowess, and most of the specifications show that the explanatory power of variation is consistent to changes in specification and adjustment of observation, as shown by the adjusted R-squared.
Robustness Check:
The regression result shows that there is a positive relationship between agricultural output and money supply (MS) as well as interest rate (INR); as the coefficients are positively signed. The agricultural output is negatively related to inflation volatility and exchange rate. The F-statistic value of the model is statistically significant. The coefficient of determination ( ) of the model is very high (98.6%) which indicates that about 98.6 percent of the variation in agricultural output is jointly explained by the explanatory variables specified. The value of the adjusted (0.9859) which is over 98% reaffirms the high goodness of fit and it signifies that over 98.6% variations did not merely result from the use of multiple variables in the model.
With respect to the signs of the independent/explanatory variables, not all the variables are rightly signed as it does not confirm with the a-priori expectations. The result indicates that a unit increase in money supply and interest rate would bring about 1.1564 and 0.03088 increase respectively in agricultural output implying a positive relationship. On the other hand, inflation volatility and exchange rate which are negatively signed indicates that they have an inverse relationship with agricultural output. This implies that a unit increase in these variables (i.e. inflation volatility and exchange rate) will bring about -7.24 and -0.006414 units decrease in agricultural output.
The implication of the above result with respect to the variable of interest (is that inflation volatility) is that it has a negative influence on agricultural output. Initially, in the early years agriculture contributed largely to the economy, however, due to the discovery of crude oil the investment to this sector and contribution from this sector to the economy has reduced. As the pivotal sector for any economy in its prime, the neglect of this sector has led to a fluctuation in agricultural output and as such the sector did not experience a consistent upward movement in growth.
| Variables | Model I Coefficients | Prob. | Model II Coefficients | Prob. | Model III Coefficients | Prob. | Model IV Coefficients | Prob. |
| Exchange Rate | 3.6329 | 0.0143 | 2.0903 | 0.0696 | 2.1308 | 0.0638 | ||
| Inflation Rate | 16.2265 | 0.796 | 27.4496 | 0.5828 | 18.5844 | 0.6999 | ||
| Interest Rate | -56.0363 | 0 | -51.7992 | 0 | -51.9735 | 0 | ||
| Money Supply | - | - | - | - | - | - | - | - |
| Inflation Rate Volatility | -62.4253 | 0.0006 | -43.1047 | 0.003 | -42.3549 | 0.0024 | -39.2582 | 0.0014 |
| Constant | 63.5908 | 0.6931 | 75.293 | 0.0004 | 7.9528 | 0.0001 | 80.8734 | 0.0001 |
| Trend | 20.3604 | 0 | 29.1802 | 0 | 24.7022 | 0 | 24.6862 | 0 |
| Diagnostic Statistics | ||||||||
| R-Squared | 0.8599 | 0.8907 | 0.8934 | 0.8938 | ||||
| Adjusted R-Squared | 0.8561 | 0.8877 | 0.8898 | 0.8909 | ||||
VI. CONCLUSION
This study investigated the impact of volatilities of selected macroeconomic indicators on agricultural growth in Nigeria. First, this research established the existence of inflation volatility in the Nigerian economy for the period under study using GARCH techniques. With a volatility level of 0.9961, inflation rate in Nigeria can be described as volatile. It was observed that inflation volatility has a significant, negative impact on agricultural growth for the period 1981:1 to 2018:4. This study concludes that inflation volatility in Nigeria has a strong and negative influence on agricultural growth in Nigeria. This is in line with the study of Idowu and Hassan (2010) which discovered that inflation negatively influences real growth.
a) Policy Recommendation
As the agricultural sector is the pivotal sector for an economy like that of Nigeria, there is need to consider the effect of inflation volatility on this vital sector. Based on the findings of this study, the study recommends the following:
The government needs to put in place measures aimed at maintaining price stability in the country. The government could employ fiscal policy measures such as the built-in stabilizer under compensatory fiscal policy, since fiscal policy is mainly for stabilization.
The government should increase its investment on the agricultural sector so as to revive the sector as the improvement of this vital sector would have a positive multiplier effect on the economy.
Appropriate institution and 'checks' should be put in place to monitor the government's investment into the agricultural sector and ensure that the allocation to the agricultural sector is properly utilized.