
I. INTRODUCTION
The literature highlights that a bubble is a common empirical phenomenon in stock markets, yet there is no agreement on the driving mechanisms behind it. When a bubble occurs, prices escalate rapidly, resulting in the significant overvaluation of listed stocks. Typically, a bubble is followed by a crash. The substantial impact of major crashes on households, banks, and the overall economy underscores the importance of bubbles and crashes in investment risk management, garnering considerable attention in recent times. However, the literature presents diverse findings, with different studies revealing contrasting relationships across various countries. Furthermore, a single study has identified varied relationships for different countries. In addition, the research on Bangladesh showcases a wide range of findings. This diversity in findings reveals that predicting the stock market's response to the economy during crisis is challenging, emphasizing the importance of continuous research in this field.
The Dhaka Stock Exchange (DSE) has encountered two instances of inefficient and irrational fluctuations since its establishment, one in 1996 and the other in 2010 (Ahmed, Uchida and Islam, 2012). However, the crisis of 1996 was particularly severe, when the market index surged from 337.97 points to 4071.68 points during the bubble period and then plummeted to 647.98 points in the meltdown period. This drastic change has created a structural instability[^1](Matin, 2019). However, a small number of empirical study that have delved into the reasons behind the stock market bubble and its collapse in 1996 (Islam and Ahmed, 2015). Is it, as commonly claimed, a result of investors' speculative zeal? Or more mundane factors such as mismanaged monetary policy or other noneconomic influences be the primary drivers behind this phenomenon?
In this backdrop, this study has examined the relationships between the stock market and economy around the catastrophe of 1996. The relationships have been assessed separately both in the bubble and meltdown periods to compare the influences of the priced factors across different conditions of the stock market. Unlike previous studies on Bangladesh (Ali, 2011; Quadir, 2012; Khan and Yousuf, 2013) this study has employed an advanced cointegration technique to elucidate relationships between the stock market and the economy during the crisis times. It also tries to pinpoint the underlying factors behind the 1996 stock market bubble and its subsequent crash. These novel perspectives aim to fill the existing gap in the literature regarding Bangladesh in this domain. The outcomes of the research are expected to provide insights for financial regulators and policymakers to develop strategies for regulating the stock market, particularly during crisis.
II. LITERATURE REVIEW
Critics argue that stock market does not always accurately reflect the underlying fundamentals of the economy, especially, when speculative bubbles and subsequent crashes emerge in the market (Binswanger, 1999). The author has argued that under such situations, stock prices are no longer driven by macroeconomic fundamentals rather they tend towards irrational behavior. So, explaining the price pattern becomes a challenge during the crisis of the stock market. Considering the adverse effect of these extreme price movements on economy, many studies have explored the reasons behind these irrational fluctuations. Kazuo (1995) mentioned that since 1950s, Japan's stock market has gone into bubbles every ten years or so (early 50s, early 60s, and early 70s). However, the bubble of 1980s was very strong and went on for several years (late 1982 to the end of 1989). He applied the fundamental equation to decompose the changes in stock prices due to the changes in the earnings of the stocks, interest rates, and stock price appreciation expectations. The study investigates the causes of this strong bubble using quarterly data for the period from 1981 to 1994. The study confirmed that the key factor was the low nominal interest rate and also the investors' optimistic expectations on stock market. In fact, the expectations factor played the leading role in the beginning and end of the bubble period, as well as in the post-bubble period, while more blame must be given to the interest factor during the bubble period.
Azeez and Yonezawa (2006) examined the effect of macroeconomic factors on stock returns in pre-bubble (1973-1979), bubble (1980-1989) and post-bubble (1990-1998) stages using McElroy and Buremeister (1985) framework considering relatively longer period data compared to other studies on Japan. They found significant influence of money supply, inflation, exchange rate, and industrial production on stock returns in all periods, but the term structure of interest rates was significantly priced over the bubble and insignificantly priced both in pre-bubble and post-bubble periods. The risk premiums in absolute values increased during the bubble and post-bubble periods, but the variances of macroeconomic factors were not increased in the bubble period. They argued that the higher risk premiums during the bubble and post-bubble periods could be due to the increase of bubble crash risk.
Asekome and Agbonkhese (2015) examined the macroeconomic variables that contributed the market's bubble, burst, and its gradual recovery. The study covered a period from 1990 to 2013. They used Nigerian Stock Exchange (NSE) value index as the dependent variable, while gross domestic product, money supply (M2), exchange rate, capacity utilization and inflation as independent variables. The results indicated that the influence of gross domestic product and exchange rate were in conformity with the theories. However, money supply (M2) and capacity utilization had negative signs instead of positive, while inflation had a positive sign instead of a negative. The result showed that regressors could explain about 97 percent of the systemic variations of stock market returns. They argued that the negative sign exhibited by the money supply might be due to the fact that a reasonable portion of the total deposit mobilized by the deposit money banks did not translate to the domestic economy by way of credit creation. They further added that the negative sign of capacity utilization was an indication of poor performance of the manufacturing sector. The negative sign of capacity utilization was further explained by poor effective demand for final products.
While researchers have extensively documented strong link between fundamental economic activities and stock market in developed countries, it remains uncertain whether a similar relationship exists in emerging market like Bangladesh. Because these stock markets, being smaller in size and relatively illiquid compared to their developed counterparts, are more significantly impacted by global economic factors rather than domestic economic indicators. Additionally, the growing influence of foreign investors in these markets might have weaken the link between national economic variables and stock market. Particularly, explaining the price pattern during the crisis of the stock market becomes a challenge. Considering the adverse effect of these extreme price movements on economy, many studies have explored the reasons behind these irrational fluctuations.
Besides, early studies have used multi-factor asset pricing models based on the assumption that stock market returns are affected by different macroeconomic factors. Nelson and Plosser (1982) argued that majority of macroeconomic series exhibit nonstationarity, with Yule (1926) warning that regression using nonstationary time series data may lead to spurious results. In response, Granger and New bold (1974) introduced the concept of cointegration to tackle the issue of spurious regression. Subsequently, Johansen and Juselius (1990) have proposed a cointegration testing method, which, however, is limited to variables integrated of order 1. Pesaran et al. (2001) developed a novel cointegration testing method that is applicable regardless the variables are integrated at the same order. This test is based on a single
Autoregressive Distributed Lag (ARDL) equation, which is recognized as one of the greatest discoveries of the 20th century (Nkoro, E. and Uko A. Kelvin, 2016). Accordingly, recent studies by Chia and Lim (2015) and Joshi and Giri, (2015) have applied the advanced Autoregressive Distributed Lag (ARDL) cointegration approach to analyze how the stock market responds to economic conditions. By applying a straightforward liner transformation, a dynamic error correction model (ECM) can be derived from ARDL (Banerjee et al., 1993). The ECM integrates the short-run dynamics with the long-run equilibrium, without losing long-run information. The ARDL approach yields robust results even with smaller sample sizes. However, there is a noticeable absence of studies investigating the relationships between macroeconomic variables and stock market of Bangladesh using ARDL model.
The Dhaka Stock Exchange (DSE) has encountered two instances of irrational fluctuations since its establishment, occurring in 1996 and 2010. Despite these occurrences, only a limited number of studies have delved into the causes of the stock market bubble and its subsequent demise (Islam and Ahmed, 2015). Are these fluctuations primarily fueled by investors' speculative enthusiasm, or are there more mundane factors such as mismanaged monetary policy or some other factors behind this? In this backdrop, contrary to other studies on Bangladesh (Ali, 2011; Quadir, 2012; Khan and Yousuf, 2013), this study has examined the relationships between macroeconomic variables and stock market during different stages of the market using Autoregressive Distributed Lags (ARDL) approach. In addition, this study has tried to identify the factors responsible for bubble and bubble crash of 1996. These new dimensions will contribute to the void in the literature related to Bangladesh in this area.
III. METHODOLOGY
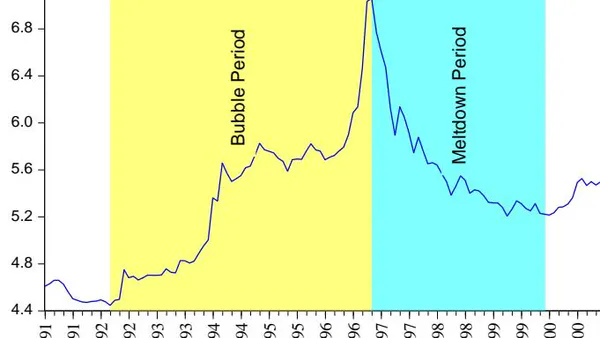
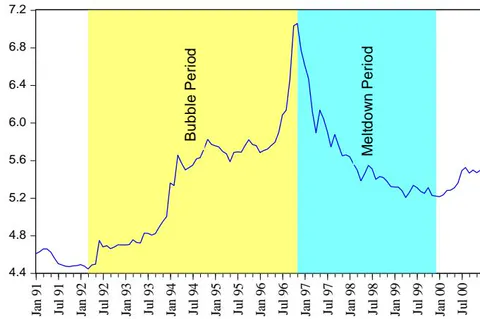
To examine the relationships between the stock market and the economy across different stages of the market, we have precisely demarcated the periods of bubble starting and crashing of 1996.From the aforesaid facts and the visual inspection of the stock market index graph (see Figure 1), we have labeled March 1992 to November 1996 as bubble period and November 1996 to December 1999 as meltdown period.
a) Sample Data
The macroeconomic variables which might have impact on future dividends and/or the discount rate from the perspective of Bangladesh economy have been considered for the study. Chen et al. (1986) have suggested that the selection of variables requires judgment. Therefore, considering the existing theory and the empirical studies of the earlier scholars - such as Maysami et al. (2004), Mukherjee and Naka (1995) and Khan and Yousuf (2013), we have used monthly data of six macroeconomic variables (see Table 1) for the period from March 1992 to November 1996 as bubble period and November 1996 to December 1999 as meltdown period. The variables are expressed in natural logarithmic forms to address various challenges, including reducing the impact of outliers, transforming skewed data to approximate normality, linearizing relationships between variables, and stabilizing variance in heteroscedastic data. The data of the DSE General Index has been collected from the Dhaka Stock Exchange Library. The data of selected six macroeconomic variables are obtained from Monthly Statistical Bulletin published by Bangladesh Bureau of Statistics, Economic Trends published by Bangladesh Bank and various editions of Economic Survey of Bangladesh. The EVIEWS 9 software is used forthe analysis.
| Variable | Symbol in Logarithmic Term |
|---|---|
| Industrial Production Index | LPI |
| Interest Rate | LINT |
| Consumer Price Index | LCPI |
| Exchange Rate | LEXR |
| Money Supply | LM2 |
| Gold Price | LGDPRICE |
b) Econometric Model
Nelson and Plosser (1982) have argued that most of the macroeconomic series have unit root indicating that the series are nonstationary. Yule (1926) has suggested that regression based on trending time series data can be spurious. This problem of spurious regression has been further pursued by Granger and New bold (1974) and they have developed the concept of cointegration. In this context, cointegration approach has been applied in this study to examine the relationship between stock market index and the macroeconomic indices at different stages of stock market. More specifically, Autoregressive Distributed Lags (ARDL), which is recognized as one of the greatest discoveries of the 20th century (Nkoro, E. and Uko A. Kelvin, 2016), has been applied in this study.
The ARDL approach crashes if any of the time series is integrated of order 2, . So, it is important to know the order of integration of the variables under consideration. Unit root tests are used for this purpose. Given the relatively low power of unit root tests, multiple unit root tests - the Augmented Dickey-Fuller (ADF) and the Phillips and Perron (PP) unit root tests, have been applied to check the stationarity and order of integration of the variables. Furthermore, whenever these two tests have given contradictory results for a variable, we have used Kwiatkowski, Phillips, Schmidt and Shin (KPSS) unit root test for conclusion. The different versions of unit root tests are set up following the Pantula (1991) principle. As per the principle, the unit root tests are started on level data with the model containing both trend and intercept (constant), because this model is the least restrictive. If the null hypothesis is rejected due to a significant test statistic, there is no need to continue testing and the alternate hypothesis is accepted. If the null cannot be rejected, then the test is carried on level data for the next less restrictive case. Based on the unit root tests results, the Autoregressive Distributed Lag (ARDL) cointegration approach has been applied.
i. Autoregressive Distributed Lag Cointegration Approach
Pesaran et al. (2001) have developed a new approach to cointegration testing which is applicable irrespective of whether the regressors are , or mutually cointegrated. The ARDL model considers a one-period lagged error correction term, which does not have restricted error corrections. Hence, the ARDL approach involves estimating the following Unrestricted Error Correction Model (UECM):
where is the differenced operator, represents the lag structure, and are the underlying variables, and and are serially independent random errors with mean zero and finite covariance matrix. In the UECM equation, where is the dependent variable, the null and the alternative hypotheses are:
[there exists no long-run equilibrium relationship]
[there exists long-run equilibrium relationship]
Similarly, for the equation, where is the dependent variable, the null and alternate hypotheses are:
[there exists no long-run equilibrium relationship]
[there exists long-run equilibrium relationship]
These hypotheses are tested using the -test ort-test. In this study, we have used -test. Pesaranet al. (2001) have discussed five cases with different restrictions on the trends and intercepts. The estimated ARDL test statistics are compared to two asymptotic critical values reported in Pesaranet al. (2001) rather than the conventional critical values. If the test statistic is above an upper critical value, the null hypothesis of no long-run relationship can be rejected regardless of the orders of integration of the underlying variables. The opposite is the case if the test statistic falls below a lower critical value. If the sample test statistic falls between these two bounds, the result is inconclusive. Once cointegration is confirmed, the short-run relationship between stock market and macroeconomic variables using ARDL models are estimated. The last step of ARDL is to estimate the associated ARDL error correction models. Finally, to ascertain the goodness of fit of the model, diagnostic tests of the residual and stability tests of the parameters are conducted. The structural stability test is conducted by employing the Cumulative Sum (CUSUM) and Cumulative Sum Squares (CUSUMSQ) tests of recursive residuals.
IV. FINDINGS OF THE STUDY
Before applying unit root tests, the stability of the VAR of each variable under two conditions -with exogenous trend and intercept, and with intercept are checked. When VAR is found stable, then the optimal lag length is determined using lag selection criterion. The summary of the optimal lag lengths is reported in Appendix A. These lag lengths are used in unit root tests for different periods. The summary of the ADF and PP unit root tests for are reported in Appendix B.ADF test for the bubble period indicates that LDSEGEN, LINT, LCPI, LEXR and LGDPRICE are integrated of order one, , while LIPI is stationary at level, and LM2 is integrated of order two, . On the other hand, PP test shows that LDSEGEN, LCPI, LEXR, LM2 and LGDPRICE are , while LIPI is stationary at level, and LINT is nonstationary with trend and constant but stationary with constant at level. In addition, PP test shows that LINT series has significant trend, so we accept the result with trend and conclude that LINT is . Therefore, only for LM2 the results of two tests are different. Thus, the KPSS test is applied to check the order of integration of LM2. The KPSS test results indicate that LM2 is . So, we can conclude that the research variables are either or in the bubble period. Further, ADF and PP tests show that LDSEGEN and LIPI are stationary at level, , while LINT, LCPI, LEXR, LM2 and LGDPRICE are integrated of order 1, in the meltdown period. So, the research variables in the meltdown period are either or .
The test for trend specification of each variable is another pre-test for cointegration analysis. To identify the most appropriate trend specification, log-likelihood ratio test for the joint hypothesis of a unit root and deterministic linear trend is used. The summary of the results of log-likelihood testis reported in Appendix C. The null hypothesis of the test is there is "no deterministic trend". The test follows Chi-squared distribution and the critical value for one degree of freedom is 3.841 at level of significance. The results show that in every period for some of the variables the null hypothesis is rejected, indicating that deterministic trend to be included.
a) Cointegration Results for the Bubble Period
The ARDL model is applied to examine the long- and short-run cointegration relationships between the stock market index and macroeconomic indices. From Appendix A, we have found that at level the dependent variable has 4 lags, and among the regressors, LINT has the highest 5 lags. So, we have set maximum lags for the dependent variable and the regressors at 4 and 5 respectively and then the automatic lag selection option is applied to allow the EVIEWS software to select the optimal laglength for each variable within the set limits. LIPI, LINT, LCPI and LGDPRICE have significant trend (Appendix C) in the bubble period, so, trend is included in the cointegration equation. The results of ARDL specification along with the Pesaran Bounds Test are summarized in Appendix
D. The Bounds test results indicate that null hypothesis of "no long-run relationship exists" is rejected and the alternative hypothesis "there exists long-run relationship" is accepted at significance level, meaning that there exists a long-run relationship between stock market index (dependent variable) and six macroeconomic indices (independent variables) in the bubble period.
The Bounds test results have showed that is 0.5268, which indicates that about 52.68 percent of the variations in stock prices can be explained by the changes in selected macroeconomic indices along with the trend. The remaining 47.33 percent is explained by other factors, which have not been considered in this research. The F value is significant at level, meaning that the regression coefficients are significant. The Durbin-Watson statistic confirms the presence of non-autocorrelated residuals. As there exists a cointegration relationship between the stock market and the macroeconomic variables, so we have examined the cointegrating form and long-run relationship. The summary of the results is shown in Appendix E. The results show that LIPI, LCPI, LEXR and LM2 are positively related with stock market index and LINT and LGDPRICE are negatively related with the stock market index. However, only LEXR is significant at level and LIPI and LGDPRICE are significant at level. The coefficient of exchange rate is significantly large compared to the coefficients of other macroeconomic variables indicating the dominance of exchange rate on stock prices.
Also, from the research data, it is found at the beginning of the bubble period the exchange rate was 1 US = 42.35 at the end of bubble period meaning that the Bangladeshi currency has depreciated by 8.73 percent. This depreciation of domestic currency has attracted a significant amount of foreign investment in Bangladesh stock market (see Table 2). On the other hand, the interest rate was 9.25 percent at the beginning of the bubble period which has been decreased to 5 percent during March 1994, then gradually increased and stood at 7 percent at the end of bubble period. This change in interest rate has created a positive impact on stock prices. So, we can conclude that the exchange rate has played a key role in the bubble creation and the falling interest rate has further intensified it. This is an important finding of this research.
| Period | Purchase of Shares in Million BDT | Sale of Shares in Million BDT | Net Investment in Million BDT |
| April 92 – June 92 | 50.80 | - | 50.80 |
| July 92 – June 93 | 387.50 | 81.20 | 306.30 |
| July 93 – June 94 | 3101.80 | 965.10 | 2136.70 |
| July 94 – June 95 | 2982.70 | 133.42 | 2849.28 |
| July 95 – June 96 | 716.80 | 1877.10 | -1160.30 |
The error correction term (ECT) is -0.2606 and corresponding -value is 0.00 (see Appendix E), which indicate that approximately 26.06 percent of the disequilibria in the long-run equilibrium path is corrected per month. Furthermore, the short-run relationships between the macroeconomic variables and the stock market index are presented in Appendix F. The results show that among the regressors industrial production has 4 terms, inflation has 2 terms, exchange rate has 5 terms, and interest rate, money supply and gold price have no term. If an independent variable has no term, it indicates that the variable does not have relation with the dependent variable in the short-run. When a variable has one term, then the significance of the variable is determined by -statistic and corresponding -value. Whereas, if a variable has multiple terms, we have used the Wald Statistics to examine whether the coefficients of the terms of that variable can jointly explain the stock market return. The test statistics follow distribution, so Chi-squared critical value is used. The summary of the Wald Test results is shown in Appendix G. The results show that only exchange rate can explain the stock
b) Cointegration Results for the Meltdown Period
From Appendix A, we have found that in the meltdown period the dependent variable LDSEGEN has maximum 3 lags, and among the regressors LEXR has market return in the short-run. So, the cointegration results confirm that exchange rate has significant relationships with stock market both in long- and shot-run.
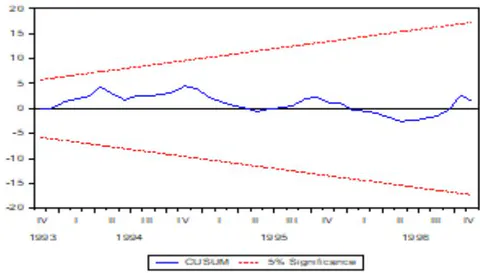
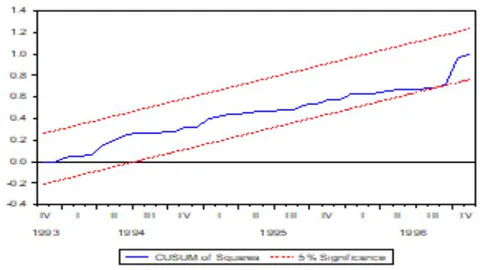
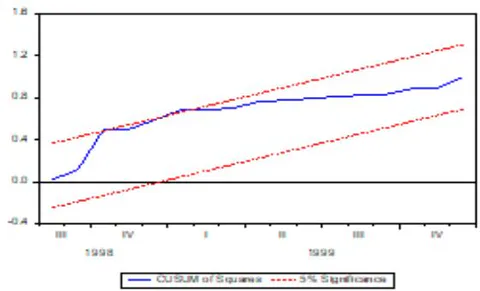
Viability checks of the model using Breusch-Godfrey Serial Correlation LM test, Breusch-Pagan-Godfrey test, and Jarque-Beratest statistic indicate that the residuals are not serially correlated and homoscedastic, but the distribution of the residuals is not normal (see Appendix H). However, practically it is hard to find a model with completely white noise residuals and the non-normal distribution of the residuals does not significantly distort the viability of the model if the residuals are homoscedastic and not autocorrelated. So, the model is a good fit model and results are significant. We have also applied Cumulative Sum (CUSUM) and Cumulative Sum of Squares (CUSUMSQ) tests to check the stability of the parameters. The results of the tests (see Figure 2 and 3) indicate that the coefficients are almost stable over the period except there is as light instability in conditional variance of the residuals at the quarter of 1996.
the highest 3 lags at level. So, we have set maximum lags for the dependent variable and the regressors at 3. Also, in the meltdown period, LIPI, LCPI, LEXR and LM2 have significant deterministic trend (see Appendix C).
So, in the ARDL test, we have included trend in the cointegration equation. The results of ARDL specification along with the Pesaran Bounds Test (see Appendix I) indicate that there exists no long-run relationship between the stock market index and the six macroeconomic indices in the meltdown period and about 36.14 percent of the variations in stock prices can be explained by the variations of the selected macroeconomic variables along with trend. The F-statistic is insignificant at level, meaning that the regression coefficients are not significant.
The results of cointegrating form and long-run coefficients are reported in Appendix J. From the results, it is evident that the coefficients of interest rate and exchange rate are higher compared to the other macroeconomic indices both in short- and long-term and have negative impacts on stock prices. However, only exchange rate is significant at level in the short-run and at level in the long-run. From the research data, it is found that at the beginning of the meltdown period, the interest rate was 7 percent and was increased to 8 percent in November 1997 and remained unchanged up to July 1999. On the other hand, the exchange rate at the beginning and end of the meltdown were BDT and respectively meaning that the Bangladeshi currency has depreciated by 20 percent. However, a significant amount foreign investments have been withdrawn during 1995-1996 and 1996-1997 (Table 3). Thus, the depreciation of domestic currency could not attract foreign investment, rather a significant foreign investment has been withdrawn in this period, which has created a negative impact on stock market. Alongside, depreciation of Bangladeshi currency has increased the cost of raw-materials and capital goods causing further negative impact on stock prices. So, the withdrawal of foreign investment and increase in production cost have played a key role for the crash of 1996. At the same time, increase in interest rate has also worsen the situation a bit more.
| Period | Purchase of Shares in Million BDT | Sale of Shares in Million BDT | Net Investment in Million BDT |
|---|---|---|---|
| July 95 – June 96 | 716.8 | 1877.1 | -1,160.30 |
| July 96 – June 97 | 518.00 | 6,186.80 | -5,668.80 |
| July 97 – June 98 | 316.00 | 517.50 | -201.50 |
| July 99 – June 99 | 95.60 | 410.70 | -315.10 |
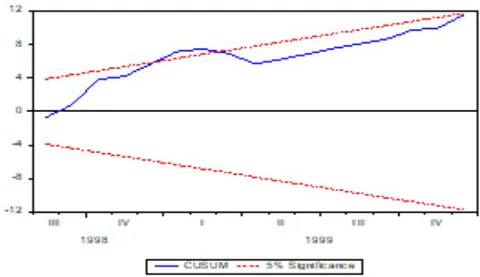
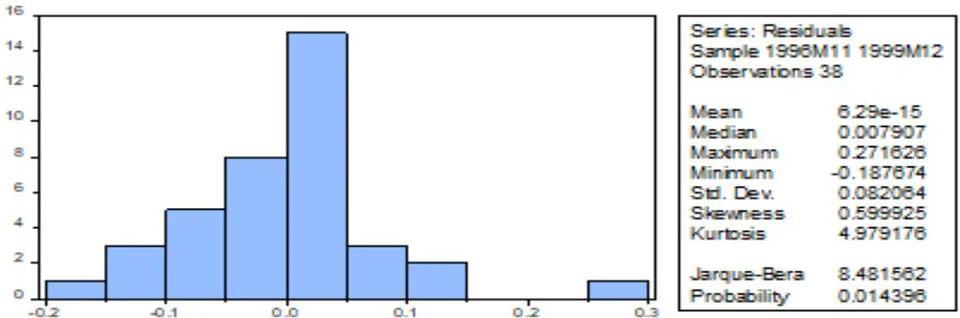
The viability checks of the model (see Appendix K) indicate that the residuals are not serially correlated and homoscedastic, but the distribution of the residuals is not normal. However, the non-normal distribution of the residuals does not significantly distort the viability of the model as the residuals are homoscedastic and not
V. CONCLUSION
The study confirmed the existence of long-run relationships between stock market and economy in bubble period while no such relationship was found in meltdown period. The explanatory power of the autocorrelated. Furthermore, the results of both CUSUM and CUSUMSQ tests (see Figure 4 and 5) indicate that the slope parameter (coefficients) and their conditional variance are unstable. So, we conclude that during the post-bubble period the parameters were unstable.
macroeconomic variables was higher in the bubble period compare to the meltdown period. These results uncovered that our stock market returns were partially driven by fad and fashions which were not related to the economic conditions. The long-run equation unfolded the dominance of exchange rate on stock prices both in bubble and meltdown periods. The depreciated Bangladeshi currency had attracted foreign investment in bubble period, the opposite had happened in meltdown period. The increased foreign investment along with consistent decreasing interest rate had boosted the equity prices in the bubble period. Conversely, the depreciated exchange rate had increased the cost of production for the firms creating negative impact on equity prices at the same time the increasing interest rate had further intensified it during meltdown period. These findings revealed that the mismanagement in policy interest rate and regulation of foreign investment within the stock market were at least partially responsible for bubble creation as well as for bubble crash of 1996. This finding of this study related to interest rate is consistent with the findings of the study of Kazuo (1995).
The viability tests of the models indicated that the models were good fit and results were significant in both the periods. Alongside, the results of the stability check of the models for different periods revealed that in bubble period conditional variance of the residuals showed slight instability at quarter of 1996 indicating a sudden change in the variance of the coefficients at that time. But during the meltdown period, the coefficients as well as the variances of the coefficients were found unstable for longer period indicating prolonged instability in the meltdown period.
The outcomes of the research are expected to offer financial regulators and policy makers some insights into the mistakes they have made earlier in terms of formulating economic and financial policies to regulate the stock market. Also, the regulator and policy makers may find the outcomes of the research helpful in formulating different policies for ensuring and creating smooth trading and investment atmosphere, controlling market strategies and assessing the degree to which the stock market may need to be reformed.
APPENDICES
Appendix A: Optimal Lag Length of the Research Variables in Different Period
| Variables | Bubble Period | Meltdown Period | ||||||
| Level | 1stDifference | Level | 1stDifference | |||||
| Trend and Intercept | Intercept | Trend and Intercept | Intercept | Trend and Intercept | Intercept | Trend and Intercept | Intercept | |
| LDSEGEN | 4 | unstable | 0 | 2 | 2 | 3 | 2 | 2 |
| LPI | 1 | 5 | 4 | 4 | 2 | 1 | 3 | 3 |
| LINT | 1 | 1 | 0 | 1 | 2 | 2 | 1 | 1 |
| LCPI | 4 | 1 | 0 | 0 | 2 | 1 | 0 | 0 |
| LEXR | 1 | unstable | 0 | 0 | 1 | 3 | 2 | 2 |
| LM2 | 3 | 3 | 8 | 8 | 1 | unstable | 3 | 3 |
| LGDPRICE | 1 | 3 | 2 | 2 | 1 | 1 | 0 | 0 |
Appendix B: Results of Unit Root Tests in Different Periods
| Variables | Bubble Period | Meltdown Period | ||||||
| ADF Test | PP Test | ADF Test | PP Test | |||||
| Trend and Intercept | Intercept | Trend and Intercept | Intercept | Trend and Intercept | Intercept | Trend and Intercept | Intercept | |
| Panel A: Data at Level | ||||||||
| LDSEGEN | -2.053 | unstable | -1.298 | Unstable | -2.093 | -3.386* | -2.647 | -5.271* |
| LPI | -4.264* | -4.495* | -3.760* | -3.594* | ||||
| LINT | -0.241 | -2.772 | -0.194 | -3.014* | -0.107 | -2.772 | -0.998 | -1.764 |
| LCPI | -3.361 | -0.930 | -2.696 | -0.917 | -2.857 | -0.464 | -2.457 | -0.419 |
| LEXR | -1.057 | unstable | -1.108 | Unstable | -3.021 | 0.036 | -3.355 | 0.059 |
| LM2 | -1.643 | -0.778 | -3.000 | -0.850 | -1.865 | unstable | -2.877 | unstable |
| LGDPRICE | -2.830 | -0.913 | -3.058 | -1.064 | -1.272 | -1.262 | -1.410 | -1.342 |
| Panel B: Data at 1st Difference | |||||||
| LDSEGEN | -6.626* | -6.626* | |||||
| LIPI | |||||||
| LINT | -7.238* | -5.019* | -8.331* | ||||
| LCPI | 7.061* | -7.061* | -5.391* | -5.391* | |||
| LEXR | -7.589* | -7.589* | -4.160* | -7.472* | |||
| LM2 | -2.191 | -2.141 | -12.03* | -4.782* | -9.564* | ||
| LGDPRICE | -5.080* | -8.680* | -6.178* | -6.178* | |||
| Panel C: Data at 2nd Difference | |||||||
| LM2 | -3.954* | ||||||
Appendix C: Results of LR Test for Trend Specification in Different Periods
| Variable | Bubble Period | Meltdown Period | ||||
| Log-likelihood with joint hypothesis of unit root | Log-likelihood with joint hypothesis of unit root | |||||
| with a deterministic linear trend | with no deterministic linear trend | Test Statistics | with a deterministic linear trend | with no deterministic linear trend | Test Statistics | |
| LDSEGEN | 43.740 | 42.634 | 2.212 | 38.850 | 38.430 | 0.840 |
| LIPI | 81.346 | 74.234 | 14.224* | 50.435 | 46.584 | 7.702* |
| LINT | 275.703 | 273.366 | 4.674* | 174.294 | 174.140 | 0.308 |
| LCPI | 171.564 | 168.697 | 5.734* | 131.651 | 127.561 | 8.180* |
| LEXR | 234.429 | 233.256 | 2.346 | 133.640 | 129.040 | 9.200* |
| LM2 | 155.094 | 153.747 | 2.694 | 106.058 | 104.002 | 4.112* |
| LGDPRICE | 161.281 | 157.909 | 6.744* | 94.579 | 94.265 | 0.628 |
Appendix D: ARDL Specification and Bounds Test Results for the Bubble Period
| Dependent Variable: D(LDSEEGEN) | ||
| ARDL Model Specification (1, 4, 0, 2, 5, 0, 0) | ||
| F Statistics | 3.963162 | |
| Critical Value Bounds | ||
| Significance | I0Bound | I1Bound |
| 10% | 2.49 | 3.38 |
| 5% | 2.81 | 3.76 |
| 2.5% | 3.11 | 4.13 |
| 1% | 3.5 | 4.63 |
| R-squared | 0.526781 | |
| Adjusted R-squared | 0.283777 | |
| F-statistic | 2.370647 | |
| Prob (F-statistic) | 0.013704 | |
| Durbin-Watson stat | 2.131741 | |
Appendix E: Cointegrating Form and Long-Run Coefficients in the Bubble Period
| Independent Variables | Coefficient | Std. Error | t-Statistics | Probability |
| Cointegrating Form | ||||
| D(LIPI) | 0.184394 | 0.231365 | 0.796981 | 0.4305 |
| D(LIPI(-1)) | -1.151429 | 0.267043 | -4.311767 | 0.0001 |
| D(LIPI(-2)) | -0.316018 | 0.262300 | -1.204795 | 0.2359 |
| D(LIPI(-3)) | -0.709270 | 0.252067 | -2.813819 | 0.0078 |
| D(LINT) | -2.913802 | 6.406871 | -0.454793 | 0.6519 |
| D(LCPI) | 2.415683 | 1.173452 | 2.058613 | 0.0466 |
| D(LCPI(-1)) | -2.144393 | 1.244572 | -1.722996 | 0.0932 |
| D(LEXR) | 6.513466 | 3.424108 | 1.902237 | 0.0649 |
| D(LEXR(-1)) | -9.215305 | 4.191567 | -2.198534 | 0.0342 |
| D(LEXR(-2)) | -12.194122 | 3.948725 | -3.088117 | 0.0038 |
| D(LEXR(-3)) | -4.275752 | 3.386559 | -1.262565 | 0.2146 |
| D(LEXR(-4)) | -12.286713 | 3.347147 | -3.670802 | 0.0008 |
| D(LM2) | 0.998090 | 0.791166 | 1.261543 | 0.2150 |
| Long Run Coefficients | ||||
| LIPI | 4.701** | 2.572 | 1.828 | 0.076 |
| LINT | -9.008 | 7.023 | -1.283 | 0.208 |
| LCPI | 4.455 | 3.656 | 1.219 | 0.231 |
| LEXR | 69.546* | 19.347 | 3.595 | 0.001 |
| LM2 | 2.245 | 4.105 | 0.547 | 0.588 |
| LGDPRICE | -7.423** | 3.705 | -2.004 | 0.053 |
| @TREND | -0.112** | 0.057 | -1.965 | 0.057 |
| Variable | Coefficient | Std. Error | t-Statistics | p-value |
| D(LIPI) | 0.288372 | 0.313918 | 0.918620 | 0.3642 |
| D(LIPI(-1)) | -0.908279 | 0.461527 | -1.967987 | 0.0566 |
| D(LIPI(-2)) | -0.403653 | 0.398482 | -1.012978 | 0.3176 |
| D(LIPI(-3)) | -0.764019 | 0.323497 | -2.361751 | 0.0236 |
| D(LCPI) | 2.300926 | 1.460061 | 1.575911 | 0.1236 |
| D(LCPI(-1)) | -1.758072 | 1.506494 | -1.166996 | 0.2507 |
| D(LEXR) | 4.947807 | 4.593005 | 1.077248 | 0.2883 |
| D(LEXR(-1)) | -8.278757 | 4.763788 | -1.737852 | 0.0906 |
| D(LEXR(-2)) | -12.34567 | 4.258267 | -2.899224 | 0.0063 |
| D(LEXR(-3)) | -5.640530 | 3.873974 | -1.456006 | 0.1538 |
| D(LEXR(-4)) | -13.41595 | 3.771929 | -3.556789 | 0.0010 |
| C | -81.00451 | 24.39265 | -3.320858 | 0.0020 |
| @TREND | -0.018506 | 0.017228 | -1.074205 | 0.2897 |
| Independent Variables | Null Hypothesis | χ2 Statistics | p-value |
| LIPI | C(1) = C(2) = C(3) = C(4) = 0 | 6.872732 | 0.1428 |
| LCPI | C(5) = C(6) = 0 | 2.883884 | 0.0895 |
| LEXR | C(7) = C(8) = C(9) = C(10) = C(11) = 0 | 18.02663 | 0.0029 |
| Independent Variables | Null Hypothesis | \chi^{2} Statistics | p-value |
| LIPI | C(1) = C(2) = C(3) = C(4) = 0 | 6.872732 | 0.1428 |
| LCPI | C(5) = C(6) = 0 | 2.883884 | 0.0895 |
| LEXR | C(7) = C(8) = C(9) = C(10) = C(11) = 0 | 18.02663 | 0.0029 |
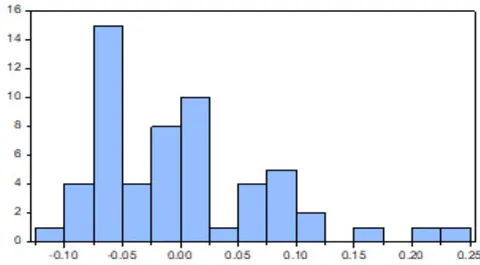
Series: Residuals Sample 1992M03 1996M11 Observations 57 Mean -1.14e-14 Median -0.011011 Maximum 0.245306 Minimum -0.112885 Std. Dev. 0.076881 Skewness 1.136590 Kurtosis 4.178711 Jarque-Bera 15.57219 Probability 0.000415 Series: Residuals Sample 1992M03 1996M11 Observations 57 Mean -1.14e-14 Median -0.011011 Maximum 0.245306 Minimum -0.112885 Std. Dev. 0.076881 Skewness 1.136590 Kurtosis 4.178711 Jarque-Bera 15.57219 Probability 0.000415
Appendix H 1.2: Breusch-Godfrey Serial Correlation LM Test
| F-statistic | 0.830237 | Prob. F(2,35) | 0.4443 |
| Obs*R-squared | 2.581717 | Prob. Chi-Square(2) | 0.2750 |
Appendix H 1.3: Heteroskedasticity Test: Breusch-Pagan-Godfrey
| F-statistic | 1.022347 | Prob. F(19,37) | 0.4610 |
| Obs*R-squared | 19.62268 | Prob. Chi-Square(19) | 0.4176 |
| Scaled explained SS | 13.14114 | Prob. Chi-Square(19) | 0.8313 |
Dependent Variable: DLDSEEGEN ARDL Model Specification (2, 0, 0, 0, 0, 0) F Statistics 1.867293 Critical Value Bounds Significance I0Bound I1Bound 10% 2.49 3.38 5% 2.81 3.76 2.5% 3.11 4.13 1% 3.5 4.63 R-squared 0.361423 Adjusted R-squared 0.156166 F-statistic 1.760830 Prob (F-statistic) 0.121482 Durbin-Watson stat 2.355889
| Dependent Variable: DLDSEEGEN | ||
| ARDL Model Specification (2, 0, 0, 0, 0, 0) | ||
| F Statistics | 1.867293 | |
| Critical Value Bounds | ||
| Significance | I0Bound | I1Bound |
| 10% | 2.49 | 3.38 |
| 5% | 2.81 | 3.76 |
| 2.5% | 3.11 | 4.13 |
| 1% | 3.5 | 4.63 |
| R-squared | 0.361423 | |
| Adjusted R-squared | 0.156166 | |
| F-statistic | 1.760830 | |
| Prob (F-statistic) | 0.121482 | |
| Durbin-Watson stat | 2.355889 | |
D(LDSEGEN(-1))
| Variable | Coefficient | Std. Error | #Statistic | Prob. |
| Cointegrating Form | ||||
| D(LDSEGEN(-1)) | 0.2640* | 0.1099 | 2.4021 | 0.0232 |
| D(LIPI) | 0.0823 | 0.2191 | 0.3754 | 0.7102 |
| D(LINT) | -6.3101 | 5.8297 | -1.0824 | 0.2883 |
| D(LCPI) | 0.7090 | 1.8046 | 0.3929 | 0.6974 |
| D(LEXR) | -5.7660* | 1.9414 | -2.9701 | 0.0060 |
| D(LM2) | -1.4900 | 1.0977 | -1.3573 | 0.1855 |
| D(LGDPRICE) | 0.1054 | 0.7871 | 0.1338 | 0.8945 |
| C | 21.2477* | 4.8689 | 4.3640 | 0.0002 |
| CointEq(-1) | -0.2626* | 0.0601 | -4.3672 | 0.0002 |
| Long Run Coefficients | ||||
| LPI | 0.1825 | 0.9503 | 0.1921 | 0.8491 |
| LINT | -25.2840 | 20.6636 | -1.2236 | 0.2313 |
| LCPI | 2.7415 | 6.5326 | 0.4197 | 0.6779 |
| LEXR | -15.6002** | 9.0198 | -1.7296 | 0.0947 |
| LM2 | -2.8238 | 6.4110 | -0.4405 | 0.6630 |
| LGDPRICE | -0.4256 | 2.5908 | -0.1643 | 0.8707 |
| @TREND | 0.0660 | 0.0893 | 0.7383 | 0.4665 |
K 1.2: Breusch-Godfrey Serial Correlation LM Test:
| F-statistic | 2.069472 | Prob. F(1,27) | 0.1618 |
| Obs*R-squared | 2.705241 | Prob. Chi-Square(1) | 0.1000 |
K 1.3: Heteroskedasticity Test: Breusch-Pagan-Godfrey
| F-statistic | 1.434836 | Prob. F(9,28) | 0.2210 |
| Obs*R-squared | 11.99393 | Prob. Chi-Square(9) | 0.2137 |
| Scaled explained SS | 12.95607 | Prob. Chi-Square(9) | 0.1646 |